Applying for an SPV Mortgage in Ireland: From Documents to Drawdown

SPV mortgage application process Ireland, director reviewing a limited company mortgage application and loan documents

Quick answer

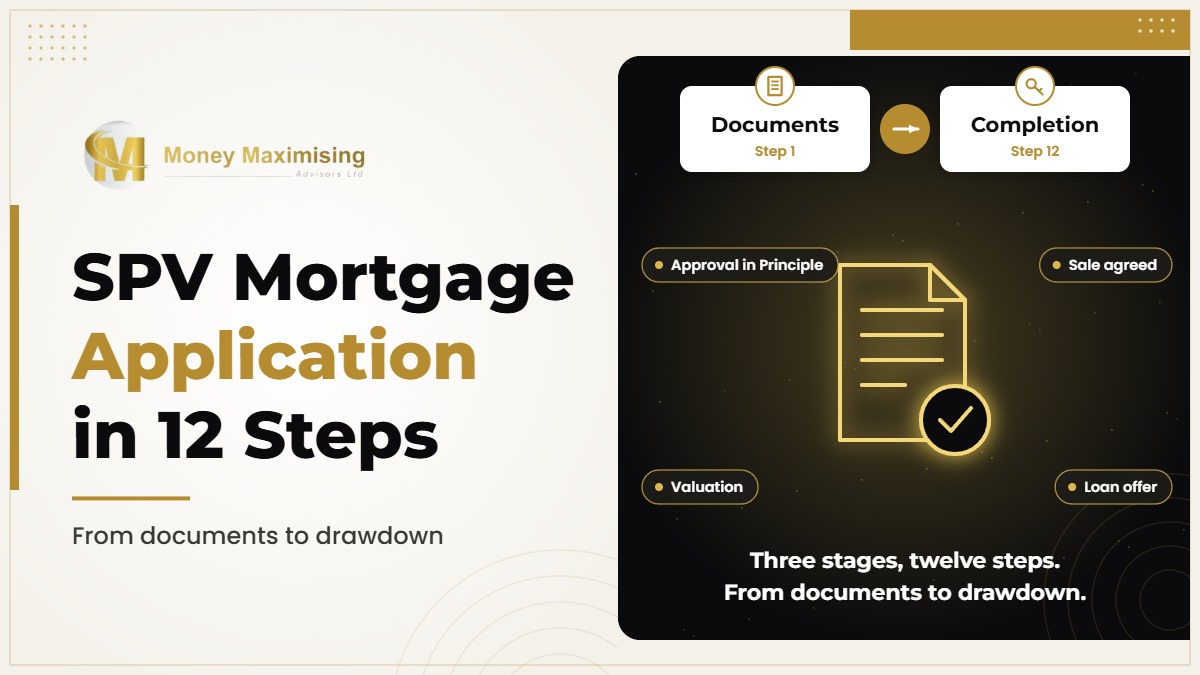
The SPV mortgage application process in Ireland usually runs in 12 steps, from documents to completion. You can often get Approval in Principle before your company is fully set up.

Steps 1 to 4

Approval in Principle

Steps 5 to 7

Company and deposit

Steps 8 to 12

Valuation to completion

Getting a mortgage through a Limited Company follows a clear sequence. Knowing the order helps you prepare documents early and avoid delays. If you are still deciding whether a company is the right route, start with our guide to buying property through a limited company.

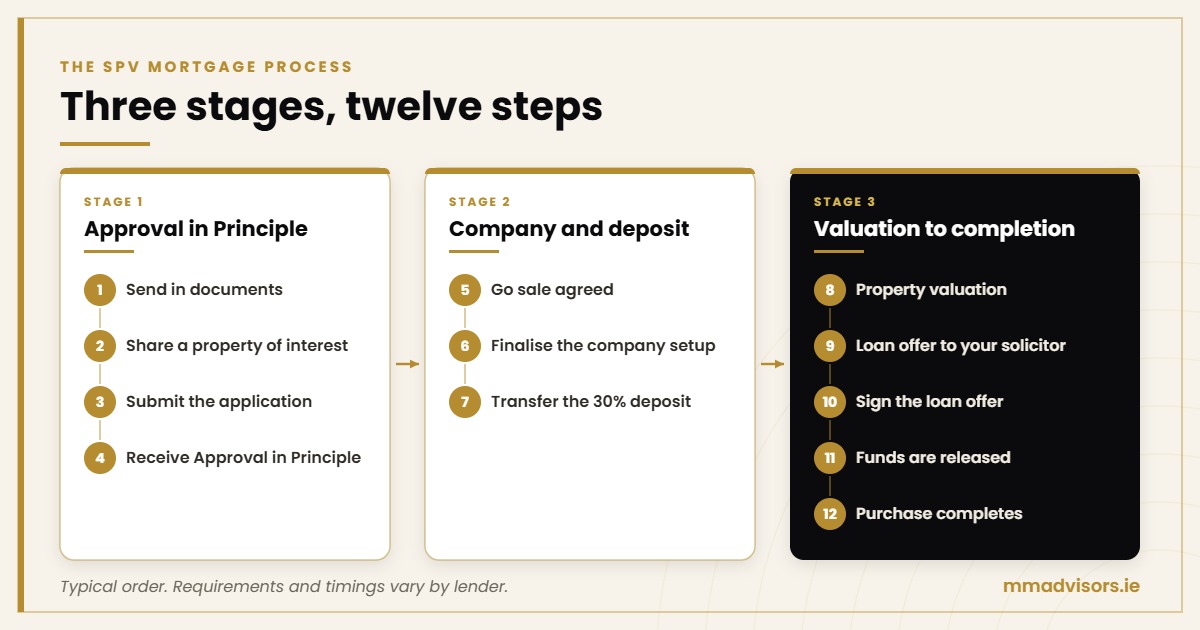
The SPV mortgage application process in Ireland in three stages and twelve steps, from documents and Approval in Principle to valuation, loan offer and completion
The 12 steps, grouped into three stages.
1

Send in your documents

Your advisor gathers the personal and financial documents the lender needs.

2

Share a property of interest

Provide a Daft link to a property you are considering. It can change later.

3

Submit your application

Your advisor submits the application to the lender.

4

Receive Approval in Principle

The lender confirms, subject to conditions, how much it may lend. Approval in Principle has an expiry date, so check how long yours lasts.

5

Go sale agreed

Agree the sale and pay the booking deposit to the estate agent.

6

Finalise the Limited Company setup

This includes registering the company with the Companies Registration Office, its company constitution and opening a company bank account.

7

Transfer the 30% deposit into the company account

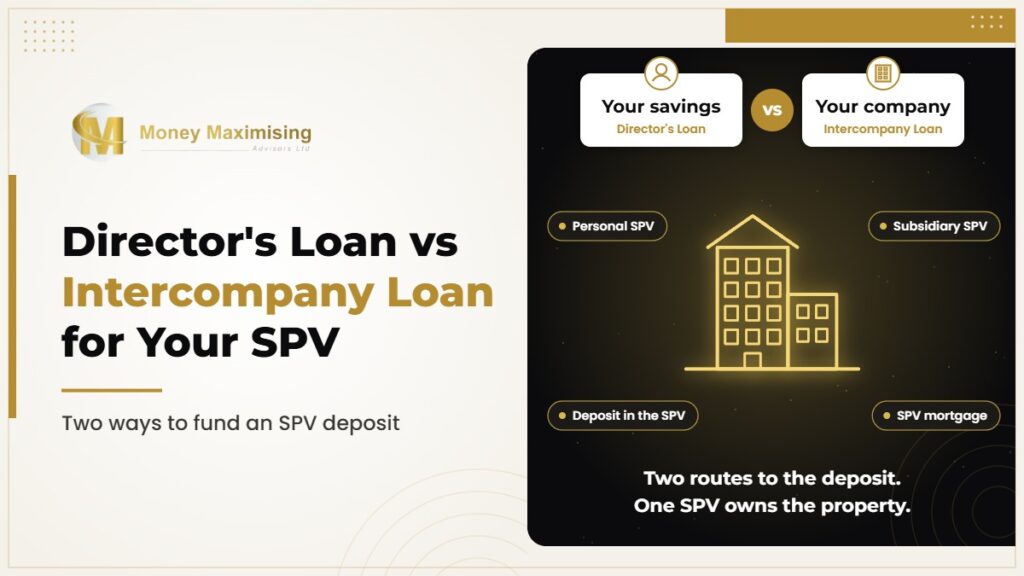
This needs to happen before the loan offer issues. How the money gets there depends on where it comes from, which we explain in director’s loan vs intercompany loan.

8

Property valuation is ordered

The lender arranges a valuation of the property it will hold as security.

9

Loan offer is sent to your solicitor

The formal offer issues once the lender’s conditions are met.

10

Sign the loan offer

Your solicitor reviews it with you before you sign.

11

The bank releases the funds

The mortgage is drawn down to your solicitor.

12

Purchase the property

The sale closes and the company owns the property.

For more on how lenders assess the company and the rent, see how an SPV mortgage works. Our step by step guide to an investment property mortgage using an SPV covers the wider investment journey.

Want help with your SPV application?

Schedule a Call
Or

Call us now (9am to 5pm, Mon to Fri)

+353 91 393 125

Requirements vary by lender. Typically:

  • ✓Photo ID and proof of address for each director
  • ✓Bank statements showing the source of the deposit
  • ✓Personal income and asset details, as directors are usually assessed
  • ✓Company documents, including the company constitution and Certificate of Incorporation
  • ✓Company bank account details
  • ✓Accounts for any existing company providing funds
  • ✓Expected rental income for the property
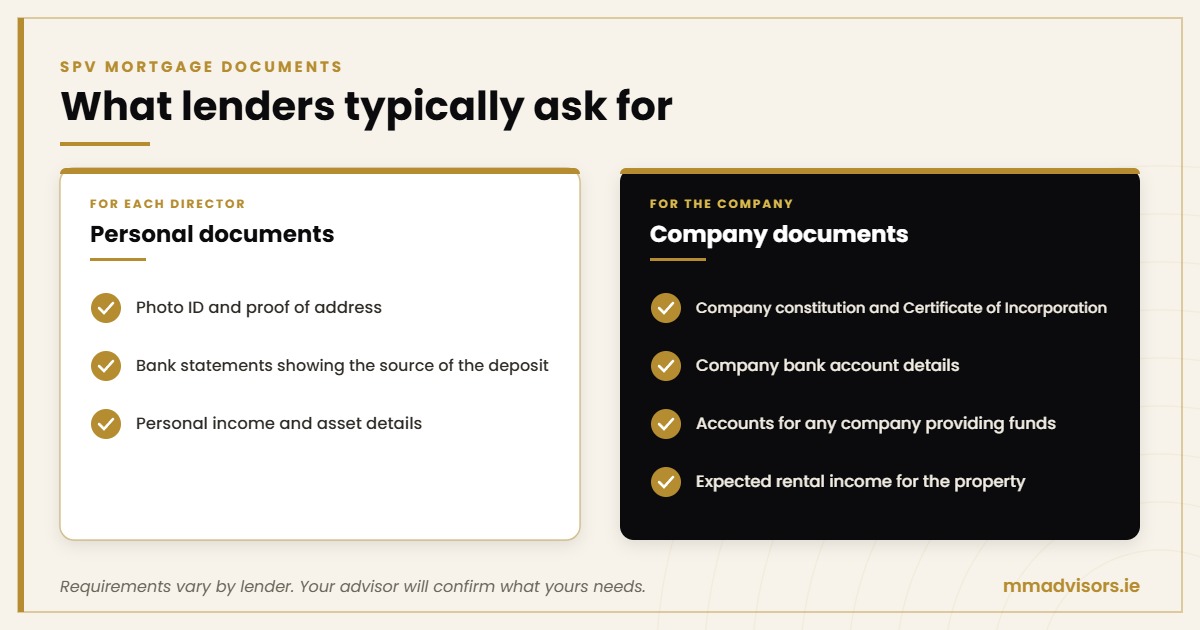
SPV mortgage documents checklist: personal documents for each director and company documents lenders typically ask for
Personal and company documents lenders typically ask for.

Where is your deposit coming from?

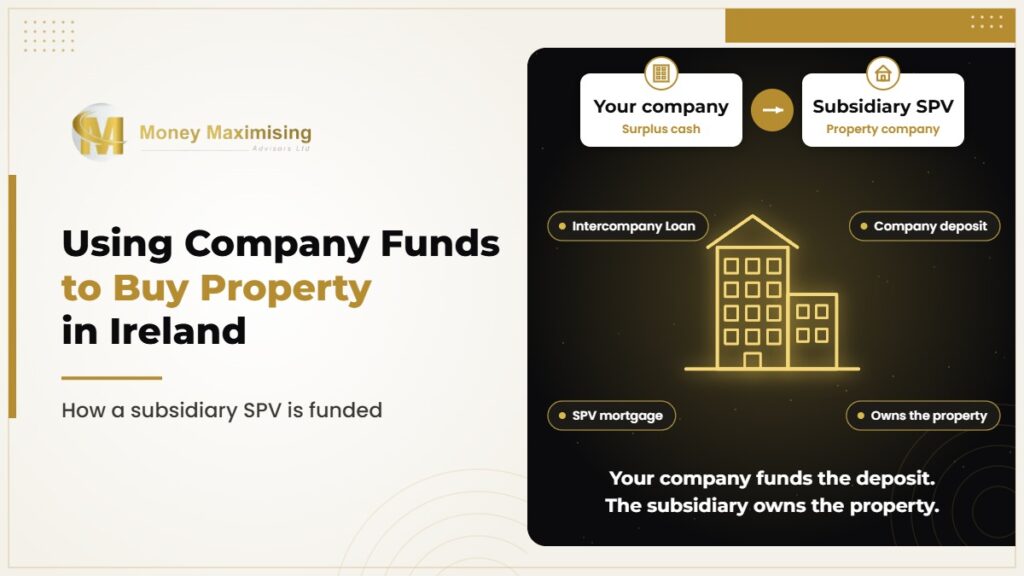
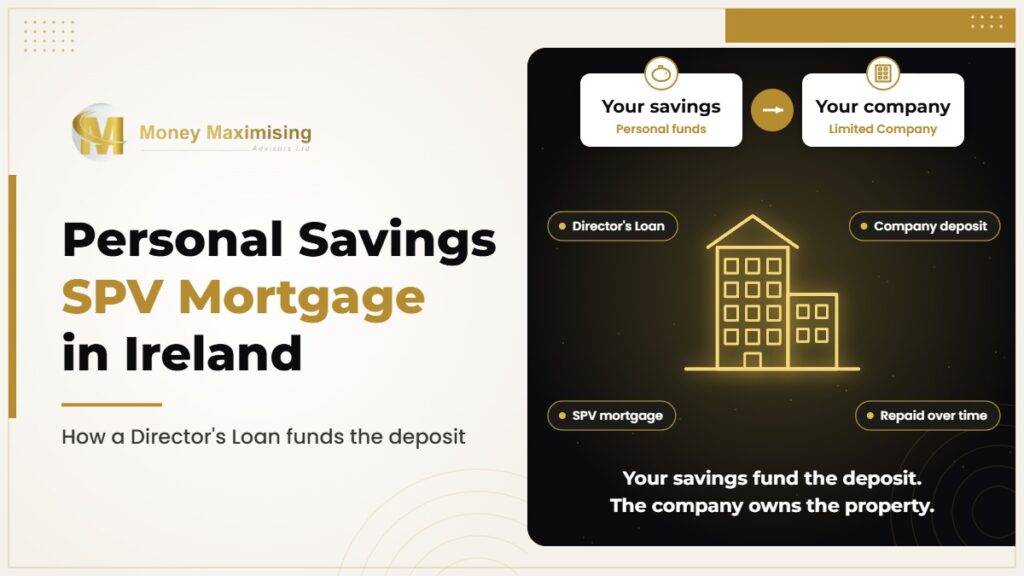
If the deposit comes from your own savings, see our guide to using personal savings for an SPV mortgage. If it comes from a business you own, see using company funds to buy property.

There is no fixed timeframe. Timings depend on the lender, how quickly documents come in, the company setup, the valuation and the property sale itself. Having documents ready and your company setup planned early is the simplest way to avoid delays.
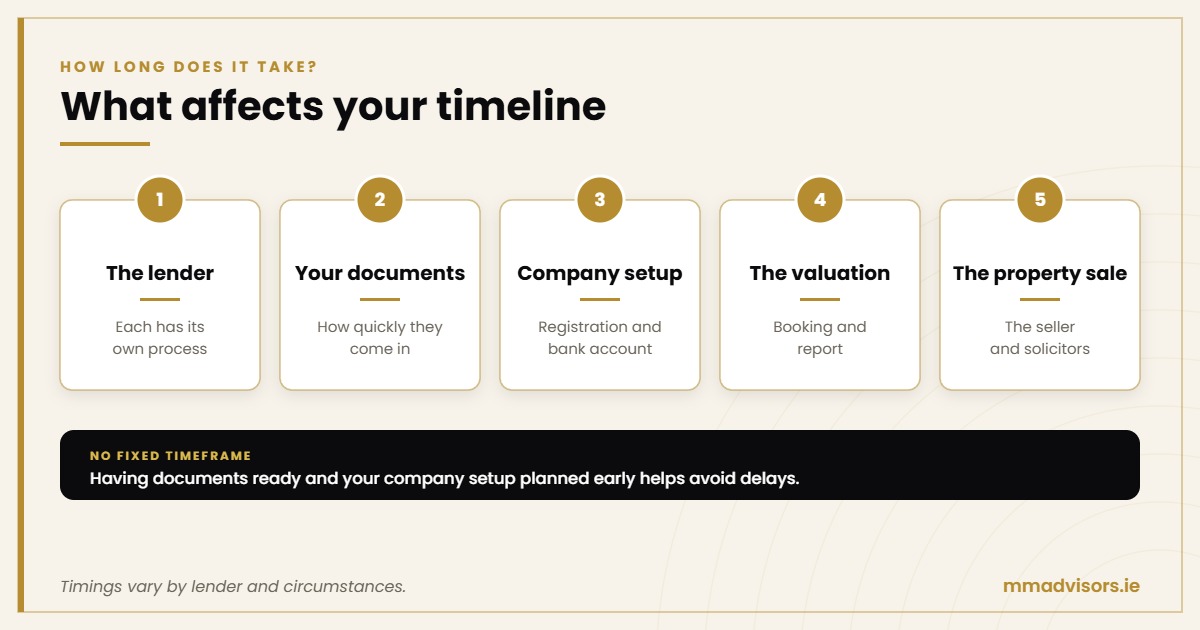
How long does an SPV mortgage take: the lender, documents, company setup, valuation and property sale all affect the timeline
Five things that affect how long your application takes.
  • ✓Start gathering documents before you find the property
  • ✓Open the company bank account early, as this can take time
  • ✓Keep a clear paper trail for the deposit
  • ✓Check the property meets lender criteria before you go sale agreed
  • ✓Compare lenders first, as criteria and SPV mortgage rates vary

Our advisors handle the application with you from the first documents to drawdown, and independent mortgage comparison advice helps match you with a lender that suits your structure. To get started, book a free mortgage consultation or read more about our SPV mortgages.

Ready to start your SPV application?

Schedule a Call
Or

Call us now (9am to 5pm, Mon to Fri)

+353 91 393 125
Do I need the company set up before I apply?+
Not necessarily. Many investors get Approval in Principle first, then register the company, open its bank account and finalise the setup before the loan offer issues. Your advisor can confirm the order your lender expects.
Can I change the property after Approval in Principle?+
Yes. The property you share at the start does not have to be the one you buy. The new property must still meet the lender’s criteria and will be valued before any loan offer is issued.
When does the deposit need to be in the company account?+
In the typical process, the 30% deposit needs to be in the company’s bank account before the loan offer issues. Lenders will check the transfer and the source of the funds as part of their assessment.
Who chooses the property valuer?+
The lender orders the valuation, usually from its own panel of approved valuers. The valuation confirms the property is suitable security for the loan, and the cost is often paid by the applicant, depending on the lender.

Important information

WARNING: If you do not keep up your repayments you may lose your property.

WARNING: The cost of your monthly repayments may increase.

WARNING: You may have to pay charges if you pay off a fixed rate loan early.

This article is general information, not financial or tax advice. Lending is subject to lender criteria and approval. The exact requirements and timings can vary by lender and circumstances.

Money Maximising Advisors Ltd is regulated by the Central Bank of Ireland. C154250.
Picture of Diarmaid Blake
Diarmaid Blake

Managing Director

Last updated

Category

Summarise this article with: ChatGPT

Related Post