Getting a mortgage through a Limited Company follows a clear sequence. Knowing the order helps you prepare documents early and avoid delays. If you are still deciding whether a company is the right route, start with our guide to buying property through a limited company.
In this guide
The SPV Mortgage Process, Step by Step
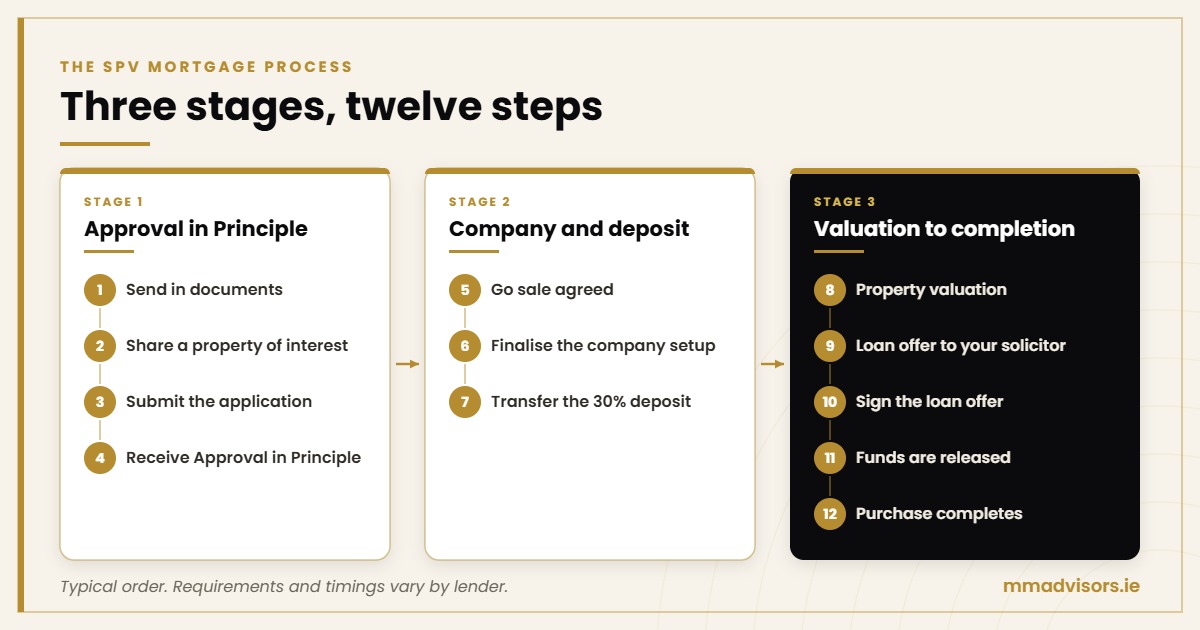
Stage 1: Getting Approval in Principle
Stage 2: Setting Up the Company and the Deposit
Stage 3: From Valuation to Completion
For more on how lenders assess the company and the rent, see how an SPV mortgage works. Our step by step guide to an investment property mortgage using an SPV covers the wider investment journey.
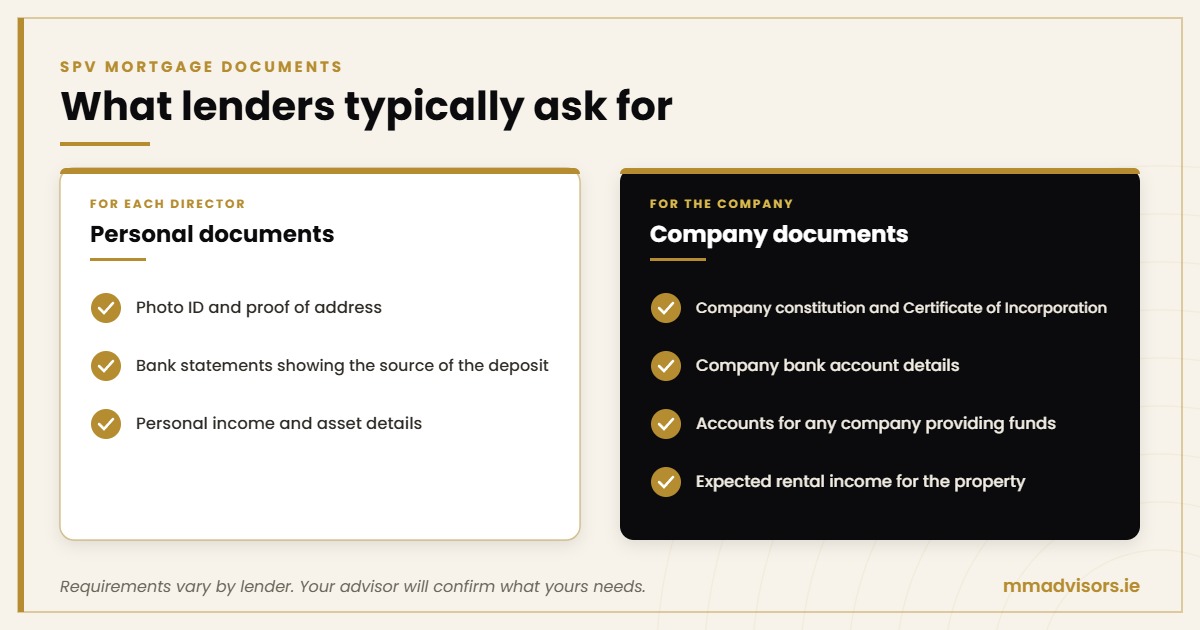
Documents You May Need
Requirements vary by lender. Typically:
- ✓Photo ID and proof of address for each director
- ✓Bank statements showing the source of the deposit
- ✓Personal income and asset details, as directors are usually assessed
- ✓Company documents, including the company constitution and Certificate of Incorporation
- ✓Company bank account details
- ✓Accounts for any existing company providing funds
- ✓Expected rental income for the property
Where is your deposit coming from?
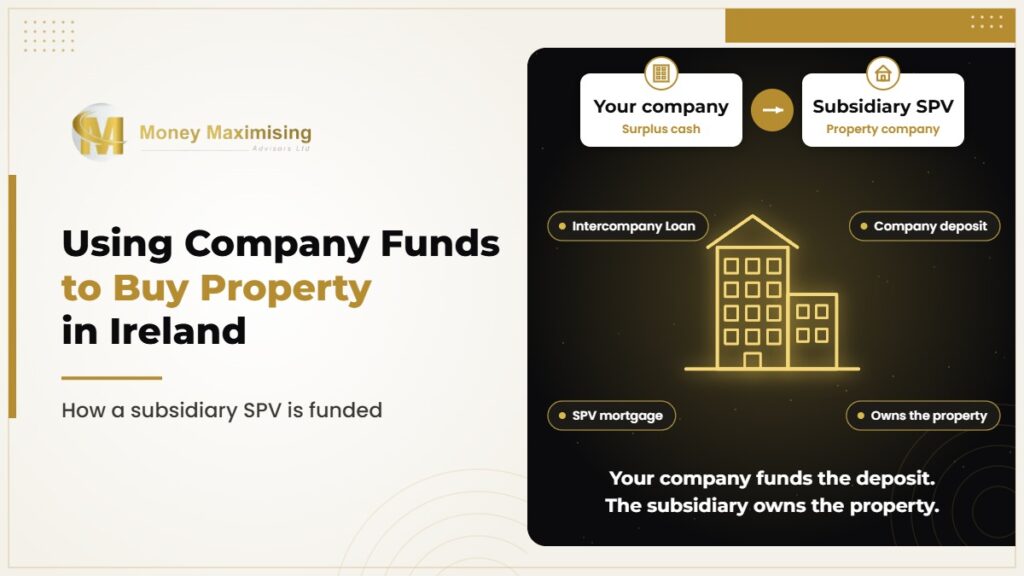
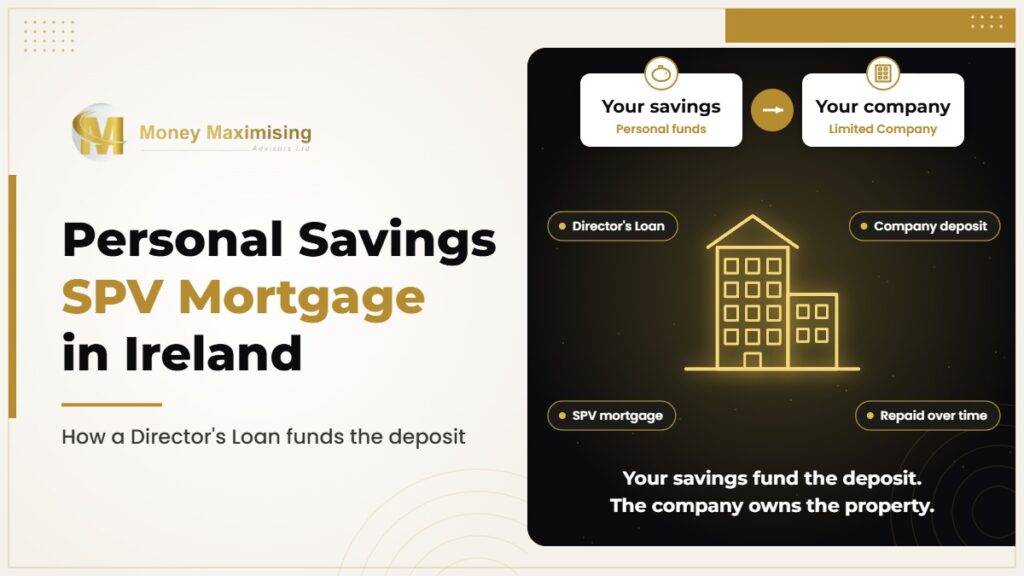
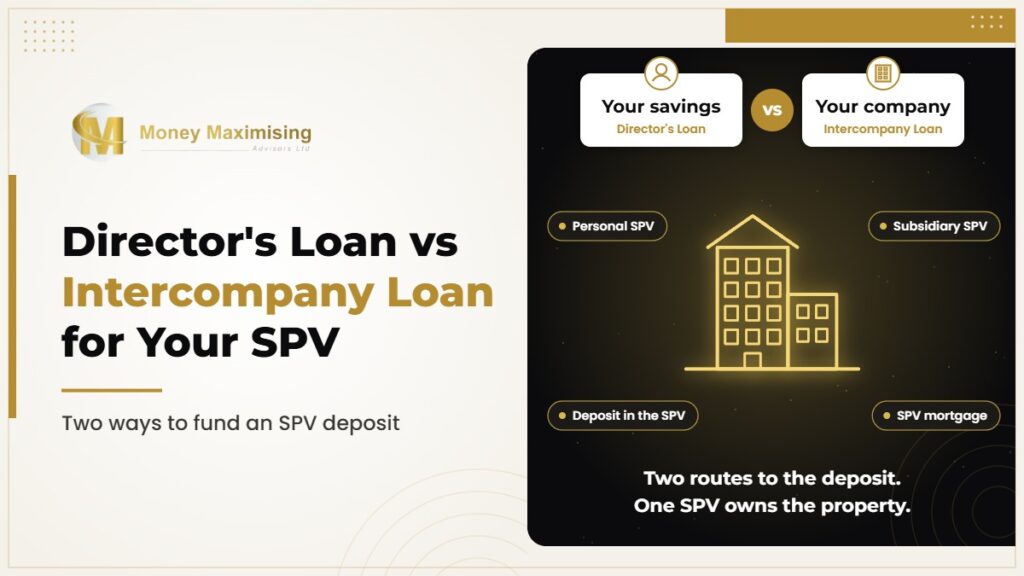
If the deposit comes from your own savings, see our guide to using personal savings for an SPV mortgage. If it comes from a business you own, see using company funds to buy property.
How Long Does It Take?
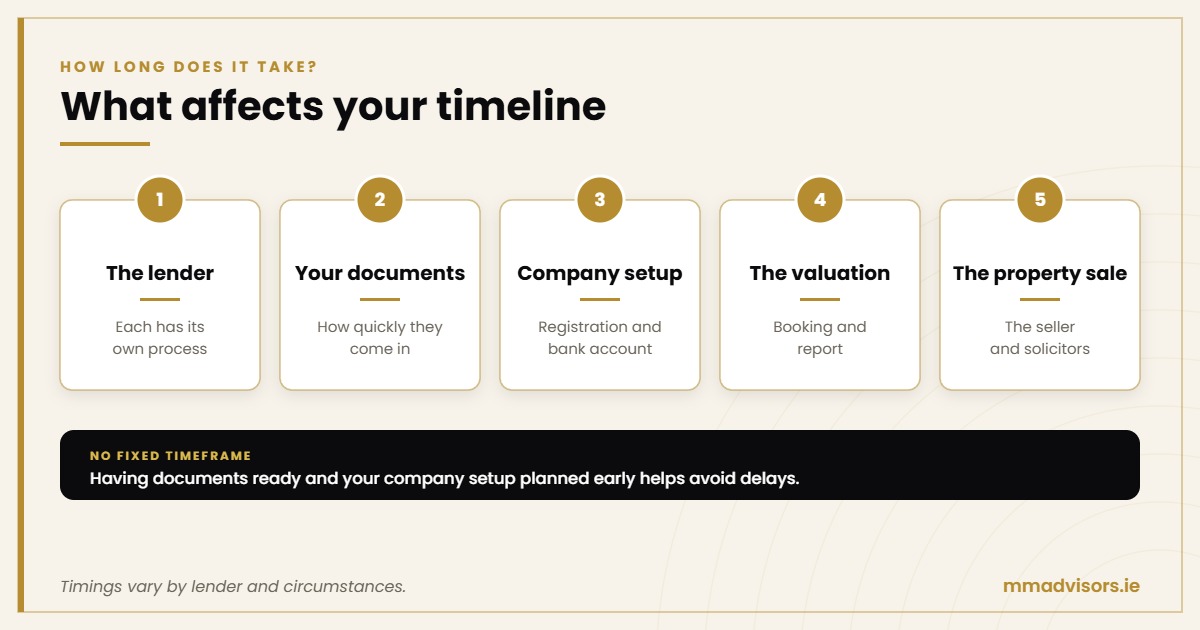
There is no fixed timeframe. Timings depend on the lender, how quickly documents come in, the company setup, the valuation and the property sale itself. Having documents ready and your company setup planned early is the simplest way to avoid delays.
Tips for a Smoother Application
- ✓Start gathering documents before you find the property
- ✓Open the company bank account early, as this can take time
- ✓Keep a clear paper trail for the deposit
- ✓Check the property meets lender criteria before you go sale agreed
- ✓Compare lenders first, as criteria and SPV mortgage rates vary
Next Steps
Our advisors handle the application with you from the first documents to drawdown, and independent mortgage comparison advice helps match you with a lender that suits your structure. To get started, book a free mortgage consultation or read more about our SPV mortgages.
FAQs
Important information
WARNING: If you do not keep up your repayments you may lose your property.
WARNING: The cost of your monthly repayments may increase.
WARNING: You may have to pay charges if you pay off a fixed rate loan early.
This article is general information, not financial or tax advice. Lending is subject to lender criteria and approval. The exact requirements and timings can vary by lender and circumstances.
Money Maximising Advisors Ltd is regulated by the Central Bank of Ireland. C154250.