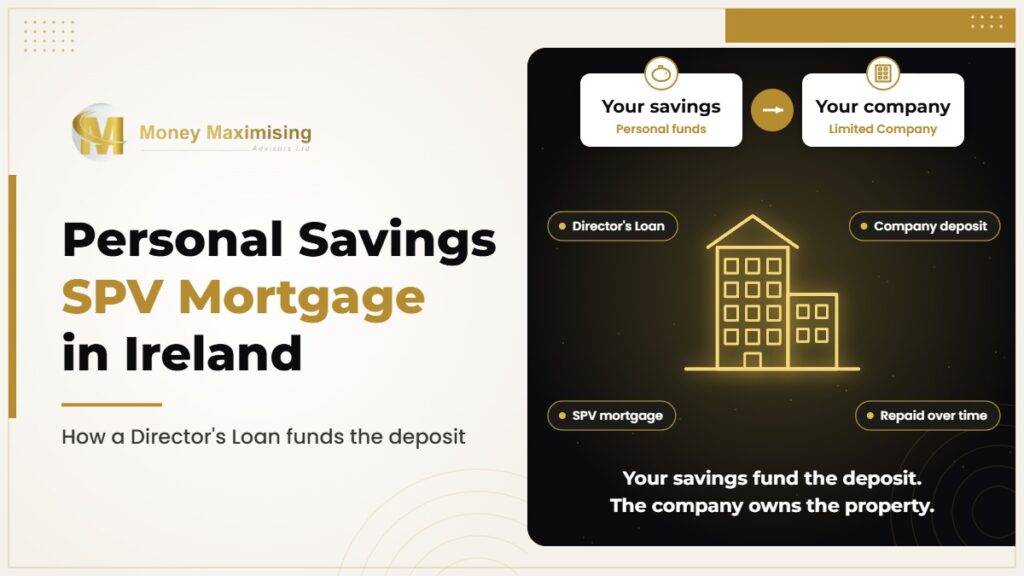
You have the deposit and you have found the property. The next question is who will finance the rest. For purchases through a Limited Company, your main bank is often not the answer, and a small number of specialist lenders lead this market. If you are new to the structure, start with our guide to buying property through a limited company.
In this guide
Which Lenders Offer SPV Mortgages in Ireland?
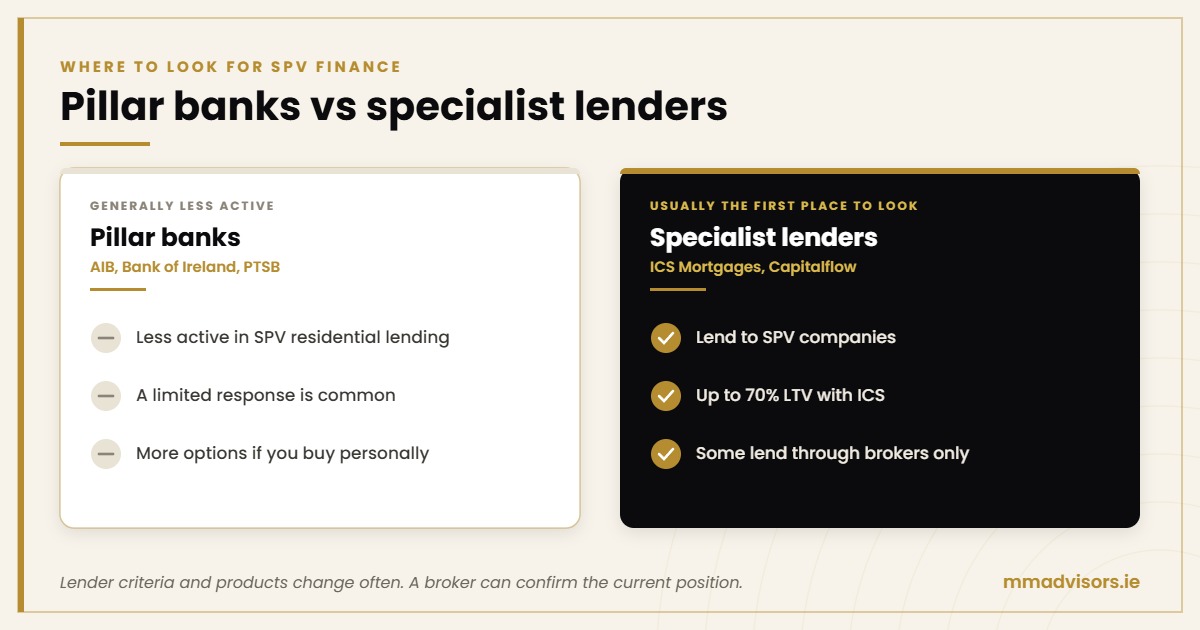
Two specialist lenders are the main providers of SPV mortgage finance in Ireland.
Specialist lender
ICS Mortgages
Offers buy to let mortgages to individuals, pension investors and companies. Companies must operate as an SPV, so a trading company cannot borrow on this product. ICS lends on variable rates only.
Entered the market April 2026
Capitalflow
Launched a residential buy to let product for individuals and SPV companies. It works only through mortgage brokers rather than lending direct to the public.
Check before you apply
Lender criteria and products change often, so a broker should confirm the current position before you apply.
How the Two Lenders Compare
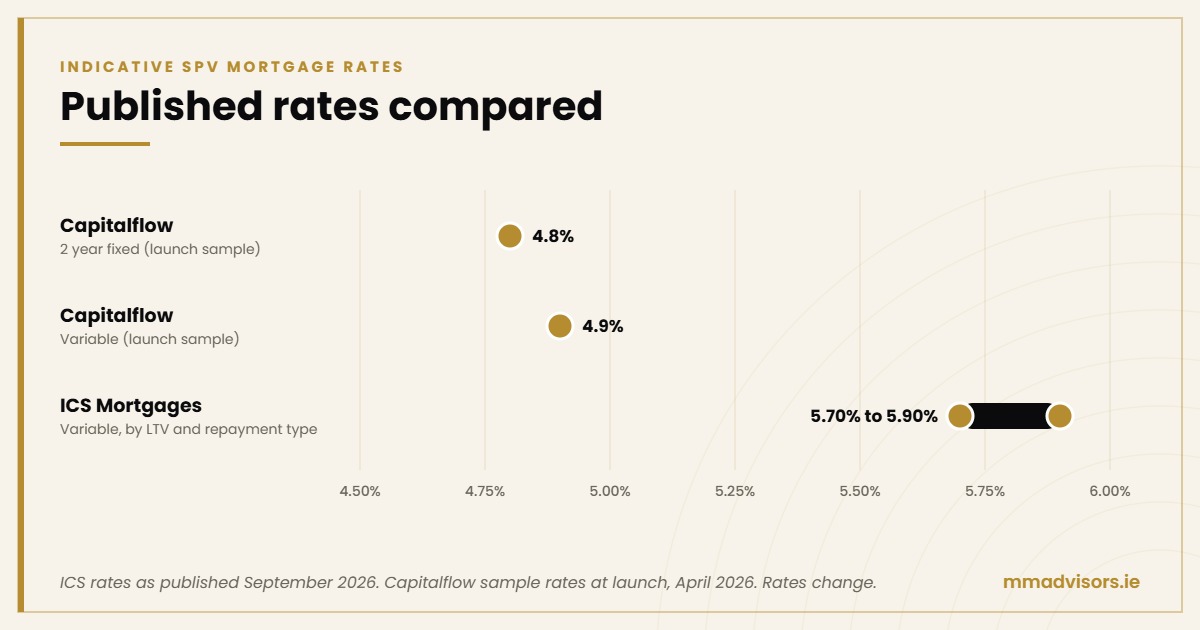
About these rates
ICS rates are as published in September 2026. Capitalflow rates are the sample rates announced at launch in April 2026 and may have changed. Rates depend on the lender, the property, the LTV and your circumstances. For more on what drives pricing, see our guide to SPV mortgage rates.
Worked Example
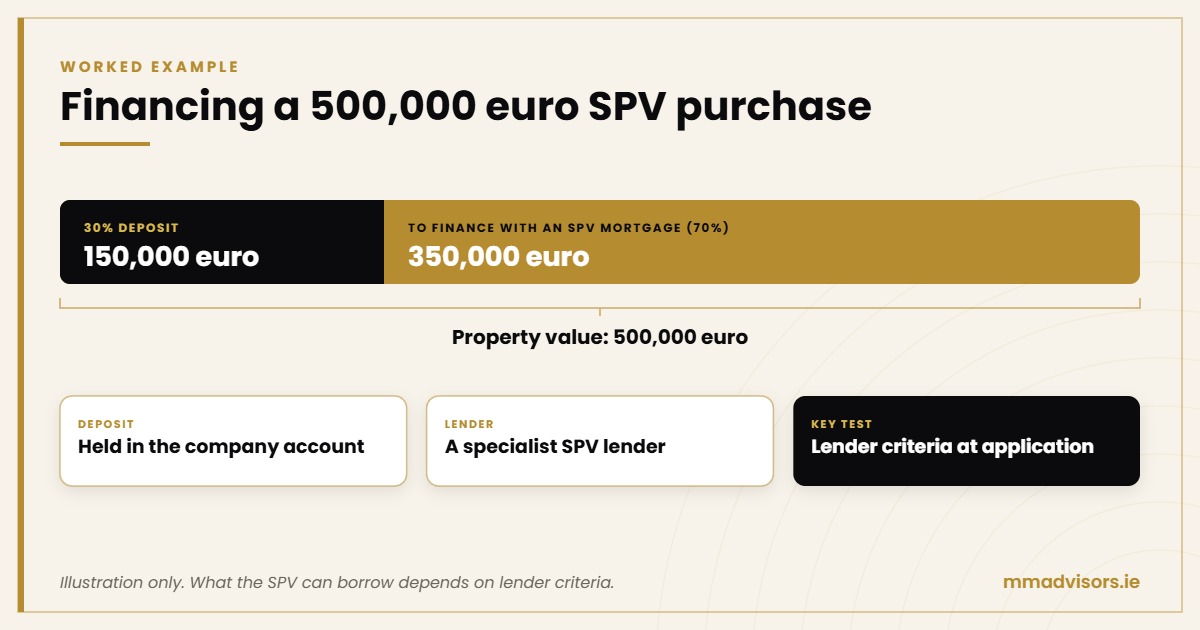
On a 500,000 euro property, a 30% deposit is 150,000 euro. That leaves 350,000 euro to potentially finance through an SPV mortgage, subject to the lender’s criteria at the time of application.
What About the Pillar Banks?
AIB, Bank of Ireland and PTSB are generally less active in lending to SPVs for residential investment property. If your own bank has given you a limited response, that reflects the shape of this market rather than your application, which is why specialist lenders are usually the first place to look. If you plan to buy in your own name instead, a personal buy to let mortgage opens up more lenders, and our comparison of buy to let mortgage rates vs SPV mortgage rates shows how the two differ.
Can I Overpay My SPV Mortgage?
Overpayment rules depend on the lender and the rate type. Variable rate mortgages generally give more flexibility, while fixed rates may carry an early repayment charge if you overpay above a set limit. Always check the terms in your loan offer.
Can I Use My Existing Company?
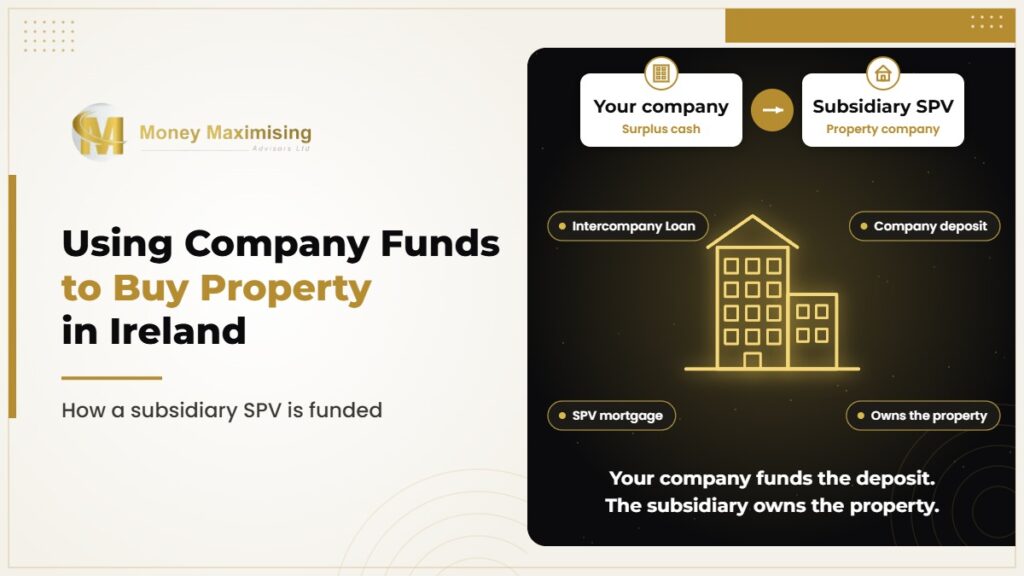
Potentially, but lenders usually want the property held in a company that does nothing else. ICS, for example, only lends to companies that operate as an SPV. The usual approach is for your trading company to set up a separate subsidiary, as explained in our guide to using company funds to buy property.
What Is the Difference Between a Normal Company and an SPV?
Limited Company
Normal company
Trades or carries out other business.
Limited Company
SPV
Set up specifically to buy and hold property.
Both are Limited Companies. An SPV is set up specifically to buy and hold property, while a normal company trades or carries out other business. See our guide to the SPV structure for how ownership and borrowing work.
Why Use a Broker?
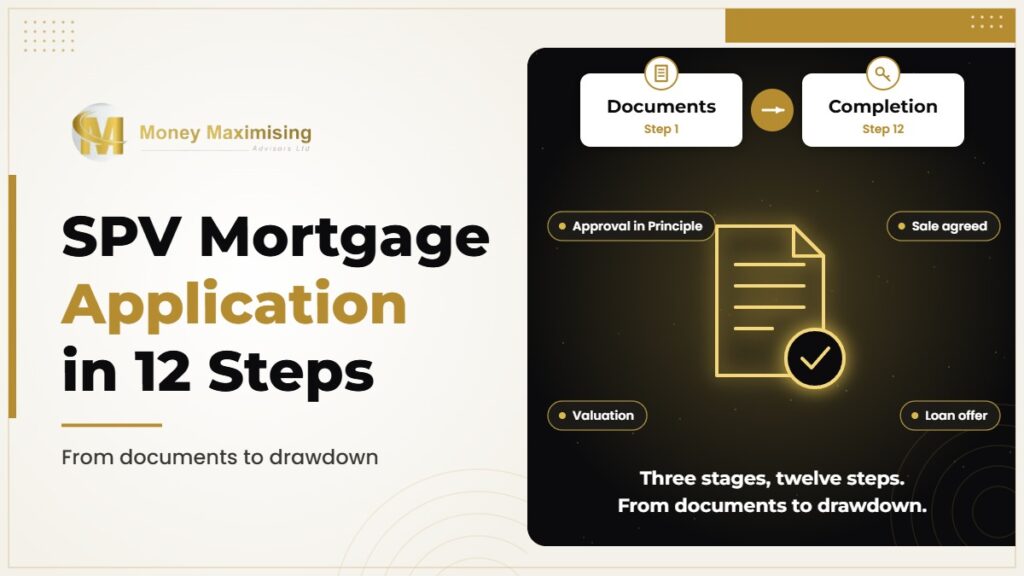
Some specialist lenders, including Capitalflow, only accept applications through brokers. Criteria also differ on property type, rental cover, loan size and how directors are assessed. Independent mortgage comparison advice matches your case to the right lender and manages the application from start to finish, as set out in our guide to the SPV mortgage application process.
To compare your options, book a free mortgage consultation or read more about our SPV mortgages.
FAQs
Important information
WARNING: If you do not keep up your repayments you may lose your property.
WARNING: The cost of your monthly repayments may increase.
WARNING: You may have to pay charges if you pay off a fixed rate loan early.
This article is general information, not financial or tax advice. Lending is subject to lender criteria and approval.
Money Maximising Advisors Ltd is regulated by the Central Bank of Ireland. C154250.