Quick answer
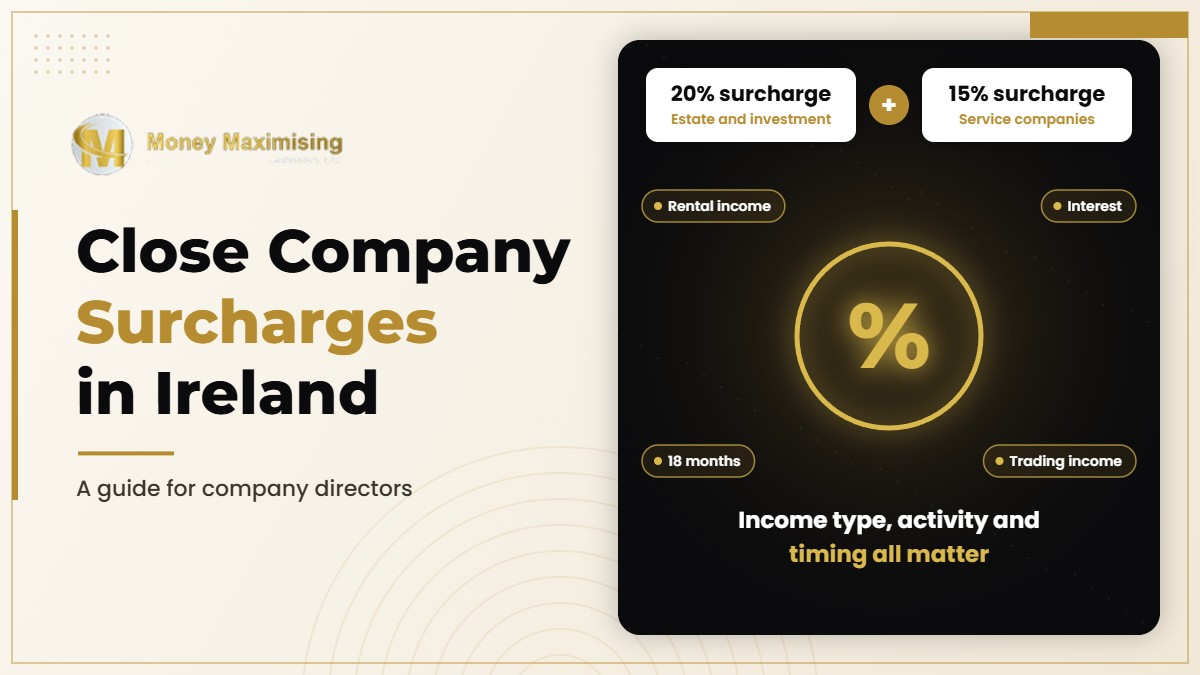
A close company surcharge can make retained income more expensive than a director expected. However, the rules do not mean every euro left in every private company is automatically surcharged. The income type, company activity, distributions and timing all matter.
This guide explains the main concepts for Irish company directors. It does not calculate a liability. The company’s accountant should classify the income and complete the Corporation Tax return.
What is a close company?
Revenue broadly describes a close company as an Irish-resident company controlled by five or fewer participators, or by participators who are directors. Many owner-managed companies fall within the definition, but the detailed control rules should be checked.
Close company status brings special provisions for benefits, interest paid to directors, loans to participators and undistributed income. It is therefore relevant even when a company carries on a genuine trade.
The 20% surcharge on estate and investment income
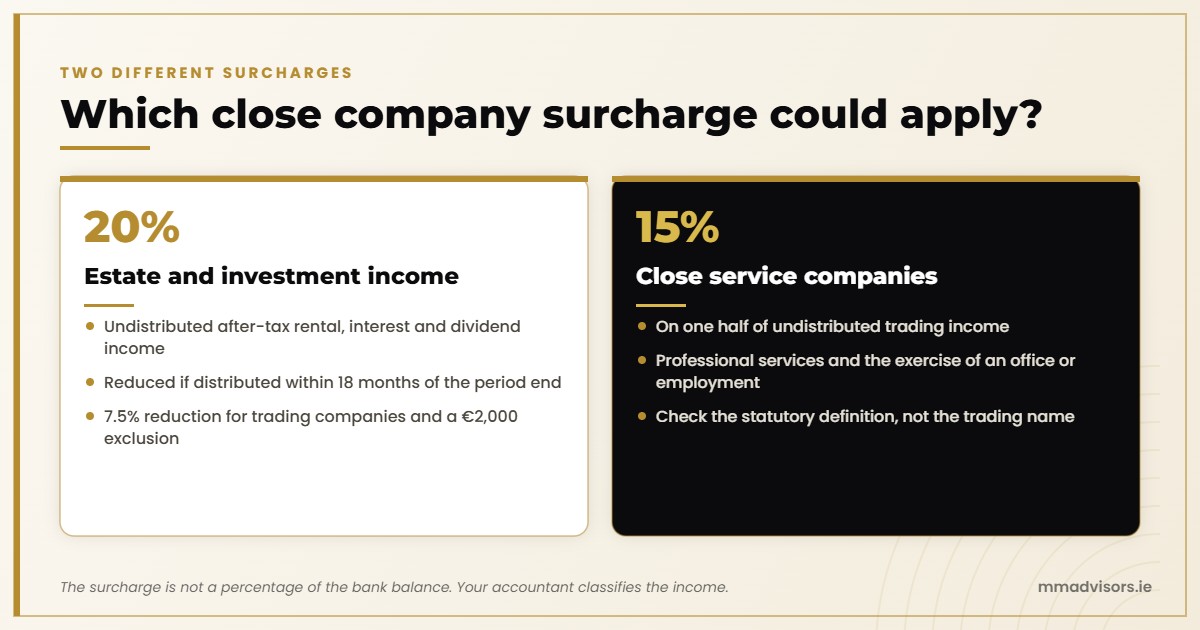
Revenue states that a 20% surcharge applies to undistributed after-tax estate and investment income of a close company. Examples include rental income, interest and dividend income. The surcharge is reduced where the relevant income is distributed within 18 months of the accounting period end.
A trading company receives a 7.5% reduction when calculating distributable estate and investment income. Revenue also describes a €2,000 exclusion where the excess after distributions does not exceed that amount. These are calculation rules for the accountant, not reasons to make an automatic dividend.
The service company surcharge
A close service company can face a separate surcharge of 15% on one half of its undistributed trading income. Revenue gives professional services and the exercise of an office or employment as examples within the rules.
A director should not assume that a company is or is not a service company based only on its trading name. The source of income and the statutory definition need to be reviewed.
Why retained cash is not the same as surcharge income
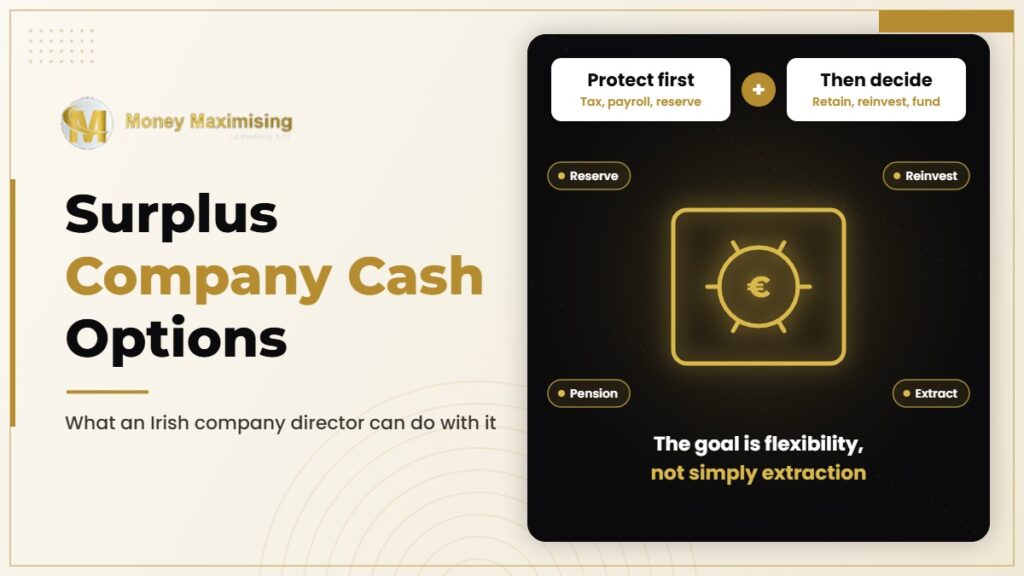
A company may retain cash for payroll, tax, debt, equipment, acquisitions or a working-capital buffer. The surcharge rules focus on categories of undistributed income and statutory calculations. They do not simply apply a percentage to the bank balance.
This distinction matters. A growing trading company may need cash, while a company accumulating investment income may have a different exposure. The accountant should reconcile the accounts, income categories and distributions.
Investments can affect more than the surcharge
Company investments may introduce market risk, product charges, tax on investment returns and a later cost when value is extracted personally. They can also affect the trading profile of a company or the availability of business disposal reliefs, depending on the facts.
Before investing long-term surplus, consider the owner of the asset, the goal, the time horizon and the likely future route for the money. Cash required for tax or working capital should not be exposed to unsuitable investment risk.
Director loans need separate attention
Taking money from the company as a loan is not an automatic tax-free alternative. Revenue’s close company rules can impose a company charge on loans or advances to participators and associates. A released or written-off loan can also become income for the borrower.
There are detailed exceptions, including a limited exception for certain full-time employees or directors without a material interest. Do not rely on an exception without professional confirmation.
A practical review checklist
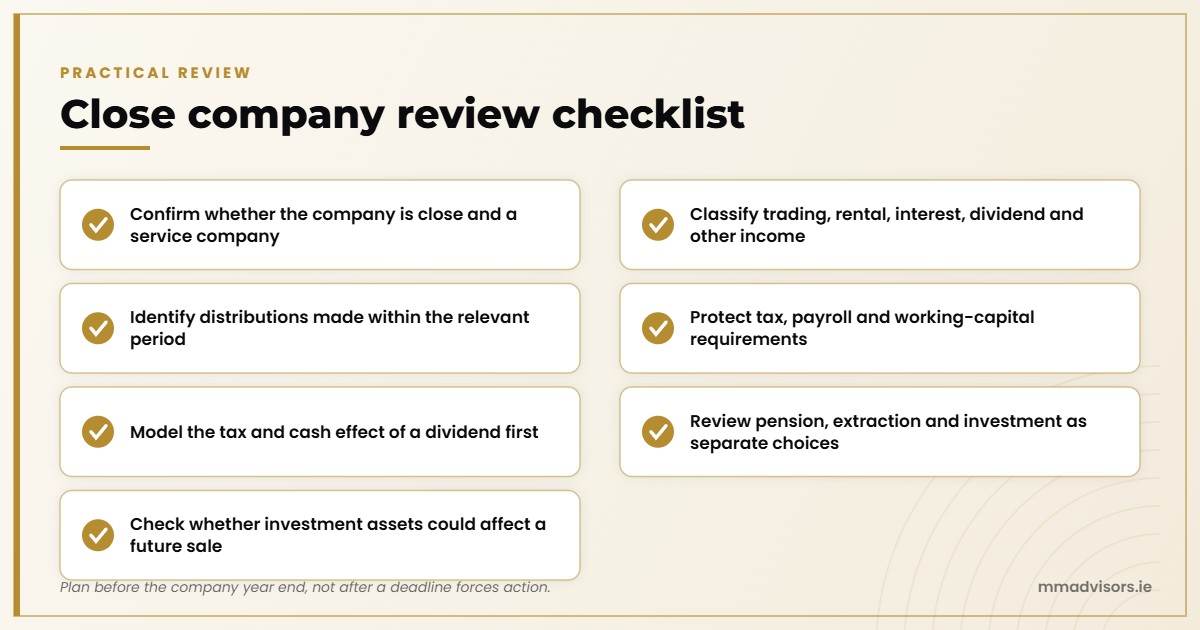
- Confirm whether the company is close and whether it is a service company.
- Classify trading, rental, interest, dividend and other income.
- Identify distributions made within the relevant period.
- Protect genuine tax, payroll and working-capital requirements.
- Model the tax and cash effect of a dividend before approving it.
- Review pension funding, personal extraction and corporate investment as separate choices.
- Check whether investment assets could affect a future business sale or transfer.
Illustrative example
A professional service company has trading income and interest earned on surplus cash. The director wants to leave all funds in the company for flexibility. The accountant first separates trading income from investment income and assesses whether the service company surcharge applies.
The director then reviews business reserves, lawful distributions, pension funding and future investment plans. The decision is based on both company and household needs, rather than a rushed attempt to eliminate one surcharge.
Questions for the annual planning meeting
- Which income categories drive the surcharge calculation?
- What must remain in the company for operations and tax?
- Would a distribution create a larger personal tax or cash-flow problem?
- Is employer pension funding affordable and within the relevant rules?
- Would corporate investments support or complicate the eventual exit plan?
Coordinate the decision before year end
Close company planning works best before a deadline forces action. The accountant confirms the tax computation. The financial adviser connects the decision to pension, investment, protection and retirement goals. The solicitor advises where ownership or agreements are affected.
MM Advisors can help company directors model the personal financial effect of different choices. Discuss your director financial plan at https://financial-planning.mmadvisors.ie/.
How to prepare for an adviser review
Prepare a schedule that separates trading income from interest, dividends, rent and other investment income. Note the accounting period in which each amount arose and any related distributions. The surcharge calculation is sensitive to classification and timing, so a bank balance alone is not enough.
Document why cash is being retained. Include tax provisions, payroll, debt, capital expenditure and an operating reserve. This record helps the board distinguish commercial working capital from money that has no current business purpose, although it does not decide the tax treatment.
Model more than one response. A distribution might reduce a surcharge but increase the shareholder’s personal tax. Pension funding may support retirement but restrict access. Corporate investing may introduce market risk and later extraction costs. The best answer can involve several actions rather than one large transaction.
Build the review into the company calendar. Discuss income classification and possible distributions before the 18-month period becomes urgent. Revisit the position after a change in company activity, ownership, investment assets or the director’s intended exit date.
Frequently asked questions
Does the 20% surcharge apply to all retained trading profits?
No. Revenue describes the 20% surcharge as applying to undistributed after-tax estate and investment income. Separate rules can apply to service companies.
What income can fall within the investment-income surcharge?
Revenue lists rental income, interest and dividend income as examples.
When can a distribution reduce the surcharge?
Revenue states that the surcharge is reduced where the relevant income is distributed within 18 months of the end of the accounting period.
Is a director loan a tax-free withdrawal?
No. Loans or advances to participators or associates can create a company tax charge and other consequences.
Should a company distribute everything to avoid a surcharge?
Not automatically. Business cash needs, personal tax, legal requirements and long-term goals must be assessed together.
Company directors
Book a director financial planning consultation
Related guides
Sources
Important information
General information only. Tax treatment depends on individual circumstances and may change. Investments can fall as well as rise, and you may get back less than you invest. Pension access restrictions apply.