Quick answer
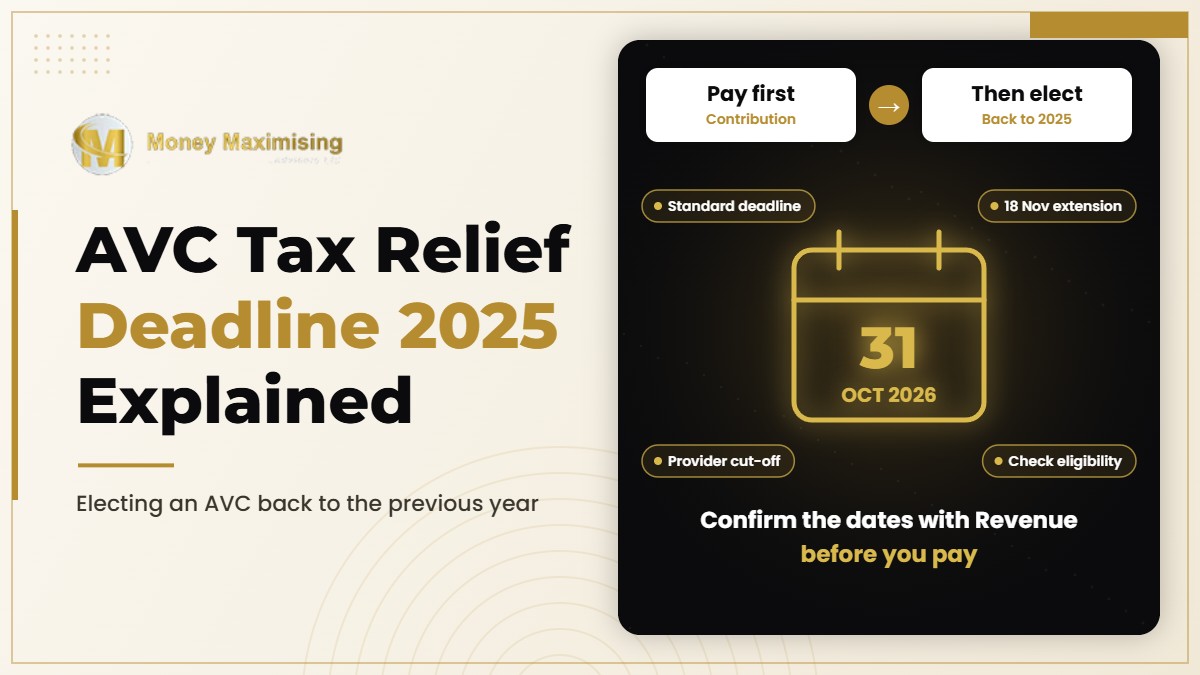
A qualifying AVC contribution may, in certain circumstances, be elected back to a previous tax year, but both the payment and the election must meet the applicable conditions and deadline. The supplied MMA review draft, checked on 22 October 2026, states 31 October 2026 as the standard deadline for 2025 relief and identifies an online extension to 18 November 2026 for eligible filers. These dates and eligibility conditions must be verified against current Revenue guidance before anyone acts on them.
Payment and election are separate steps
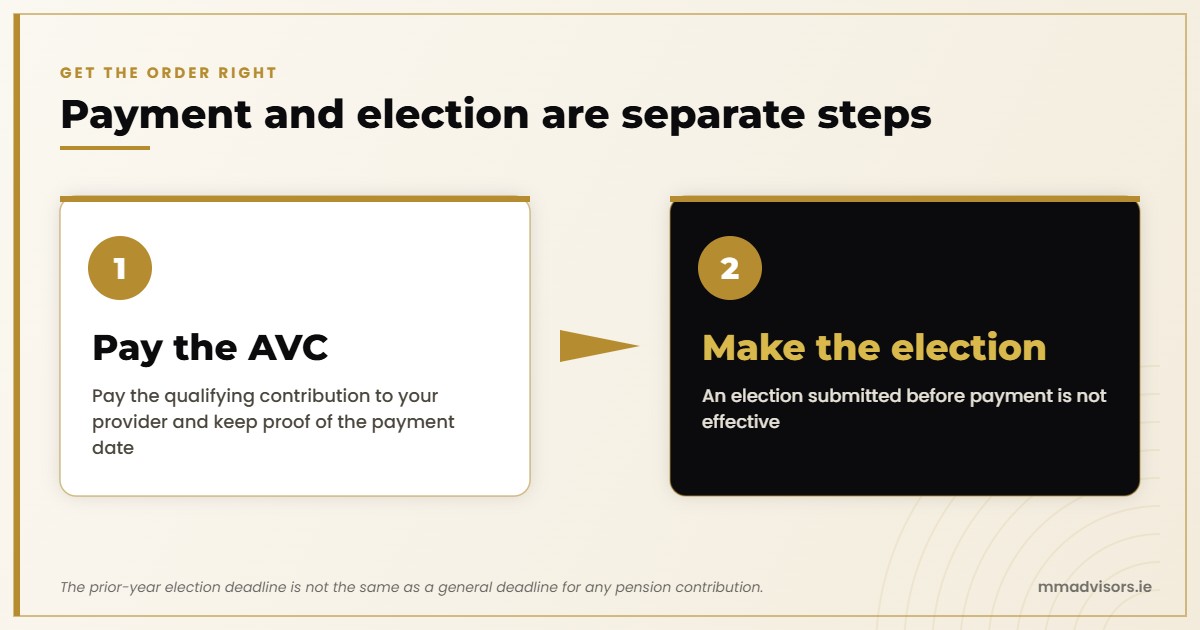
The supplied FAQ says a qualifying contribution paid after the tax year ends may be elected back to that year. It also says the contribution must be paid before the election is made; an election submitted before payment is not effective.
Do not confuse the deadline for a prior-year election with a general deadline for making any pension contribution. Eligibility depends on the arrangement, the payment date, the election process and the taxpayer’s circumstances. A provider may also have an earlier operational cut-off.
What the supplied review says about 2025 relief
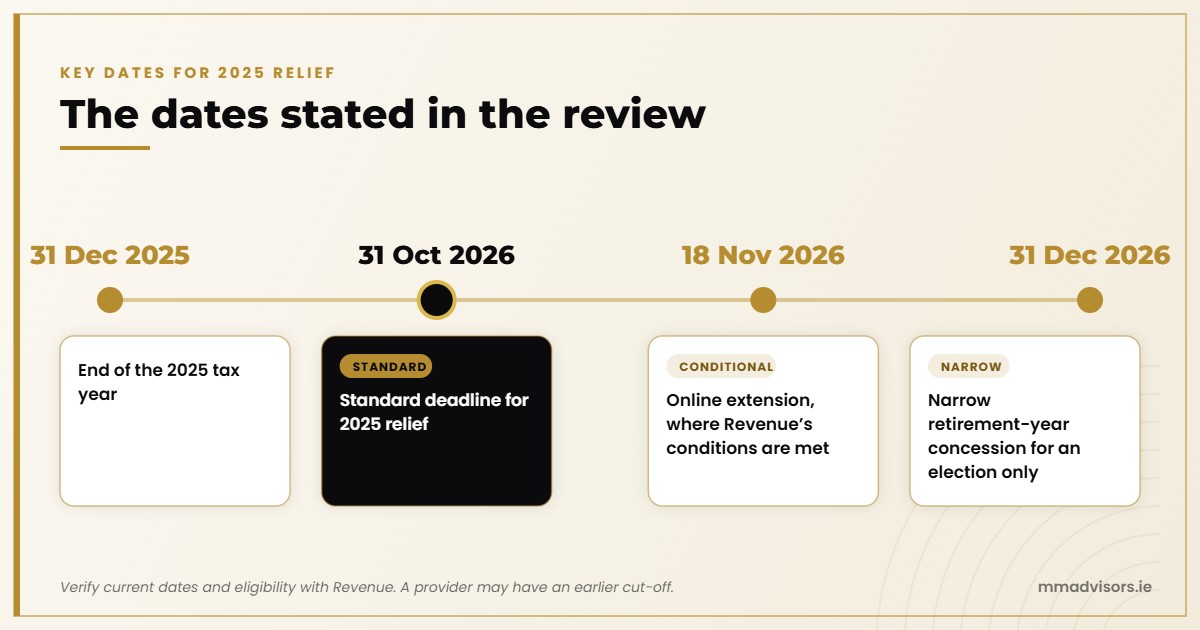
The supplied review page states that the standard deadline for 2025 relief is 31 October 2026. It also states that an online extension to 18 November 2026 may apply where Revenue’s conditions are met.
An online Revenue account alone should not be treated as proof of eligibility. The supplied guidance refers to qualifying ROS or myAccount filers and advises confirming the conditions. Before relying on an extension, check current Revenue instructions and whether the provider can process the payment in time.
A narrow retirement-year concession is not a general extension
The supplied FAQ also describes a limited retirement-year concession that may permit a later election by 31 December in the year after the tax year being claimed. For a 2025 contribution, the stated date would be 31 December 2026.
According to the supplied draft, this concession is limited to someone who is not a chargeable person for self-assessment and retires in the year the contribution is paid. It also says the contribution must already have been paid by the applicable return deadline. This is not a general extension to pay the AVC by 31 December.
Because the exception is narrow and the rules are technical, do not rely on it without confirming eligibility with Revenue or an appropriately qualified tax adviser.
Scenario: a public servant considering a late October payment
Imagine Siobhán is a public-sector employee who wants to make a one-off AVC and ask for relief against 2025. She has not yet confirmed the provider’s payment cut-off, and she is unsure whether she qualifies for the online extension.
Before transferring money, Siobhán should confirm the current Revenue deadline and her eligibility, check the provider’s payment instructions and processing time, and ensure that the contribution is eligible for relief. She should keep proof of the payment date and obtain the provider’s certificate. She should not assume that having a myAccount login or submitting documents alone completes the election.
This is an illustrative checklist, not a determination of Siobhán’s eligibility.
Do not confuse a four-year review window with the election deadline
The supplied FAQ warns that the usual four-year tax-review window does not replace the shorter deadline for electing a qualifying contribution back to a previous year. It also cautions that tax rules do not permit people to reopen retirement benefits already taken or ignore retirement contribution restrictions.
Because the dates are time-sensitive, this article should be checked immediately before publication and should link directly to the current Revenue guidance. Remove or update the deadline details as soon as the relevant tax-year window has passed.
Before you act
- Confirm the tax year you want to claim for.
- Check the current Revenue rules and whether your pension contribution qualifies.
- Confirm the applicable deadline and whether an extension applies to your circumstances.
- Ask the provider about payment instructions and any earlier processing cut-off.
- Pay before making the election, where required by the rules.
- Keep proof of payment and the provider’s contribution certificate.
- Check that relief has not already been applied through payroll or another claim.
Frequently asked questions
Can I elect a qualifying AVC contribution back to the previous tax year?
Potentially, if the contribution and election meet the relevant Revenue rules and deadlines. Eligibility must be checked for the specific payment and taxpayer.
Does having a myAccount login mean I qualify for the online extension?
No. The supplied review draft says the extension depends on Revenue’s conditions. Verify your eligibility against current official guidance.
Can I wait until 31 December 2026 to pay for 2025 relief?
Do not assume so. The supplied FAQ describes a narrow retirement-year concession for an election, not a general extension to make the payment.
Does the four-year tax-review window replace the prior-year election deadline?
No. The supplied FAQ explicitly distinguishes the usual review window from the shorter prior-year election deadline.
Related guides
- How do pension contributions affect your tax return in Ireland?: covers the broader claim process.
- Public Sector AVCs: for readers who need the public-sector AVC context.
- Revenue: the current official guidance on claiming pension tax relief.