Quick answer
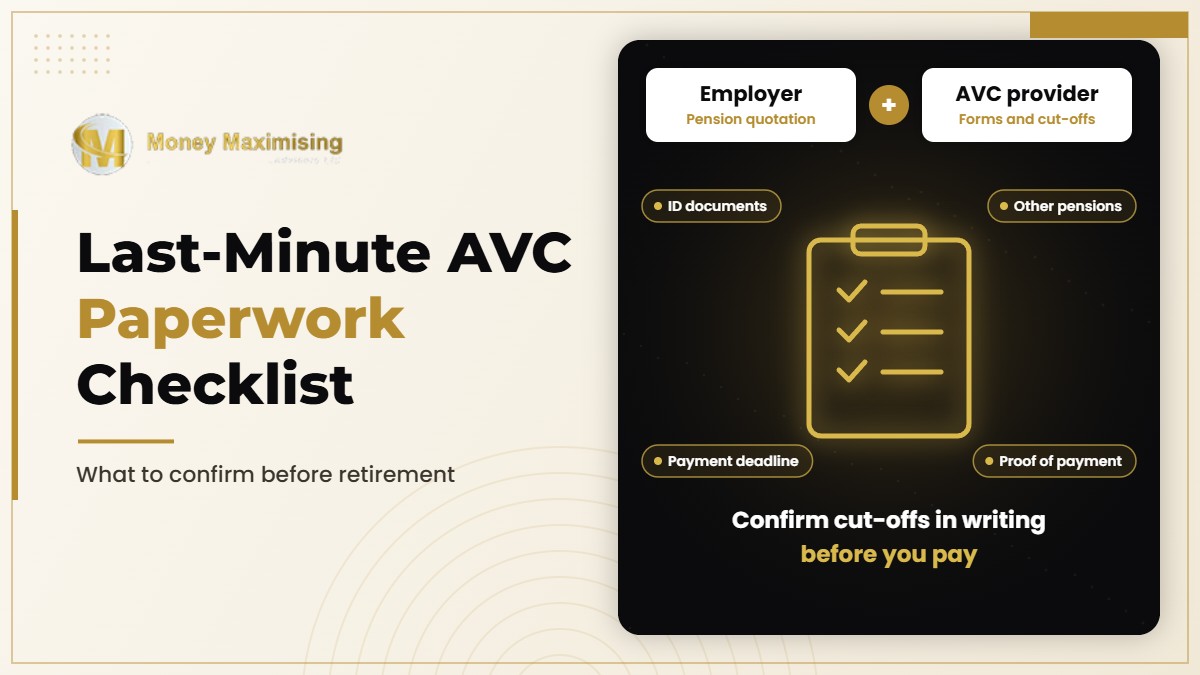
Start by asking your employer’s pension administrator and AVC provider for their own retirement checklists as soon as your retirement date is known. You may need a scheme benefit quotation, service and pay details, AVC policy information, other-pension records, identity documents and completed retirement forms. There is no single processing timetable for every provider, so confirm payment cut-offs and expected settlement dates in writing before making a last-minute AVC.
Why paperwork matters when retirement is close
A last-minute AVC is a one-off contribution intended to address a confirmed retirement cash shortfall, where one exists. The payment is only one part of the process. The employer’s final pension figures, the provider’s requirements and the rules for taking benefits all need to line up.
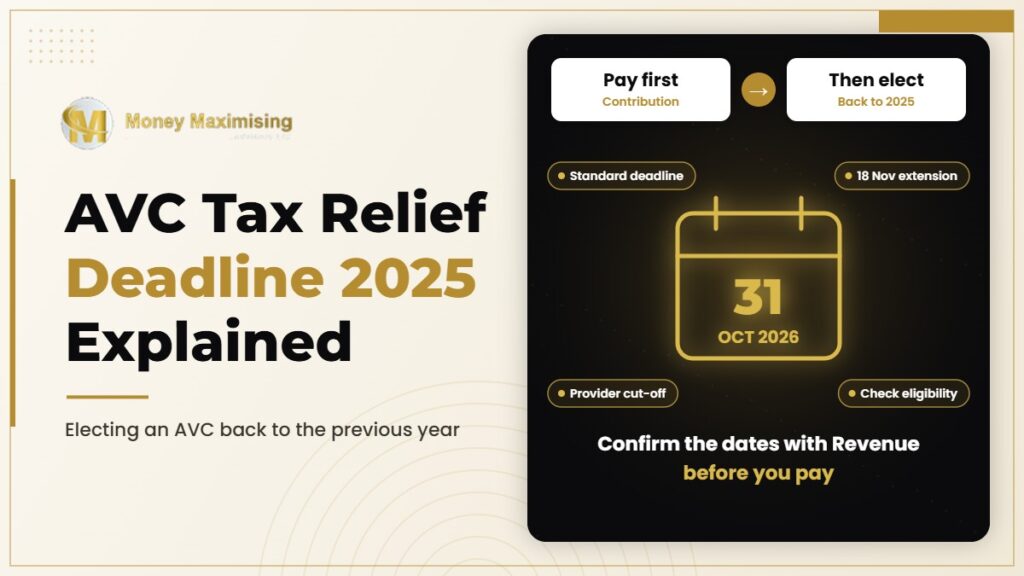
Do not assume that an October tax deadline overrides your provider’s cut-off, or that paying an AVC means the money will be available immediately at retirement. The supplied FAQ says occupational AVC benefits linked to the same employment must be taken with the main scheme benefits, although the payments do not necessarily reach your bank account on the same day.
Documents and figures to gather
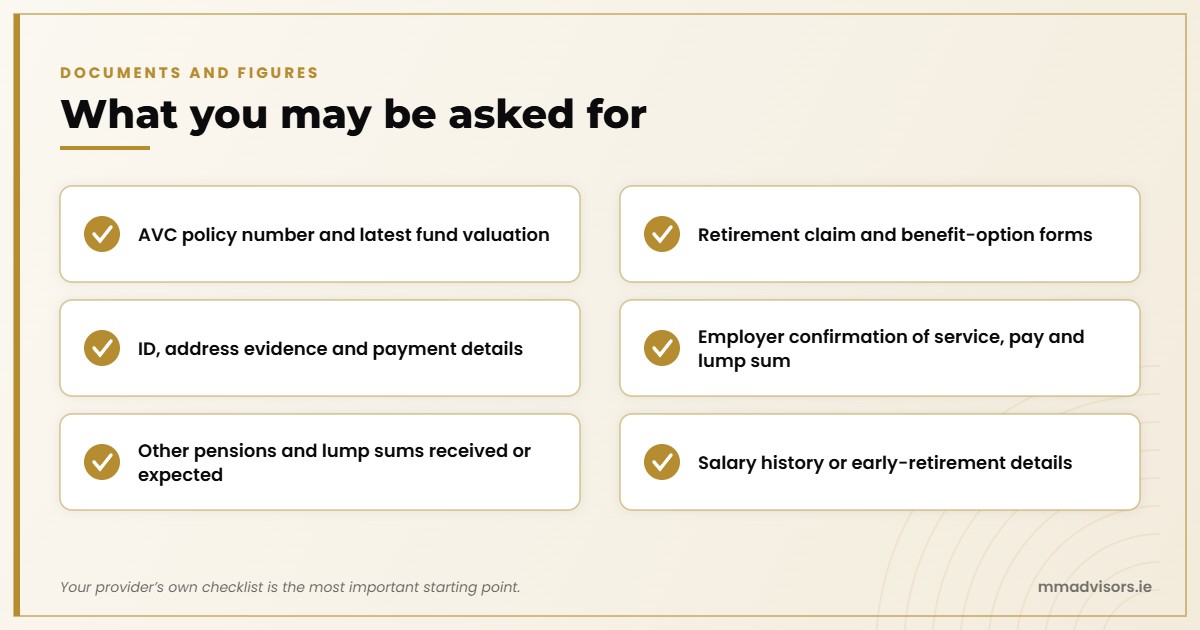
Your provider’s own checklist is the most important starting point. Depending on your arrangement, you may be asked for:
- Your AVC policy number and latest fund valuation.
- Completed retirement claim and benefit-option forms.
- Identification, address evidence if required, and verified payment details.
- Employer confirmation of your retirement date, pensionable service, pensionable pay, pension and lump sum.
- Details of other pensions and retirement lump sums already received or expected.
- Salary history or early-retirement details where they are relevant to the benefit calculation.
Some final employer figures may not be available until close to, or after, the retirement date. Ask which documents can be prepared now and which will follow later. Do not fill gaps with guesses if the provider requires confirmed figures.
Scenario: retirement is six weeks away
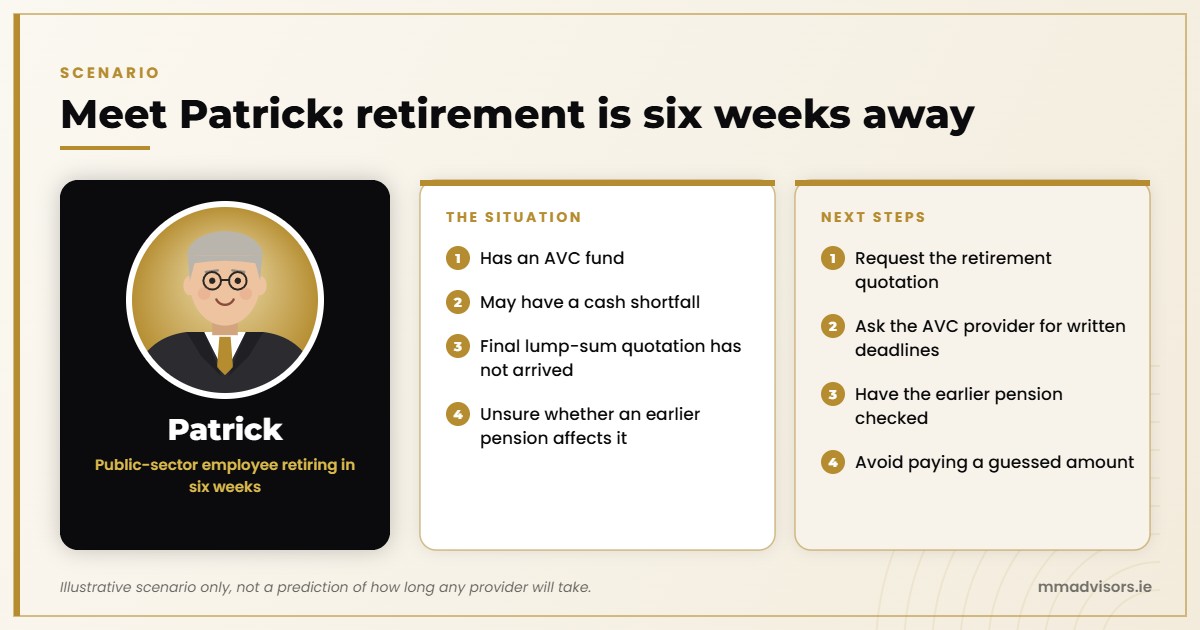
Consider Patrick, a public-sector employee whose planned retirement is six weeks away. He has an AVC fund and believes he may have a cash shortfall, but his final employer lump-sum quotation has not arrived. He is also unsure whether a pension from an earlier job affects the calculation.
Patrick should request the retirement quotation and ask the AVC provider for its written contribution and retirement processing deadlines. He should also arrange for the earlier pension to be checked. Paying a guessed amount before these questions are resolved could leave him with too much or too little funding, and may not solve the actual shortfall.
This is an illustrative scenario, not a prediction of how long any provider will take. The provider’s own cut-offs and the employee’s confirmed records determine the next steps.
Confirm the cash shortfall before paying
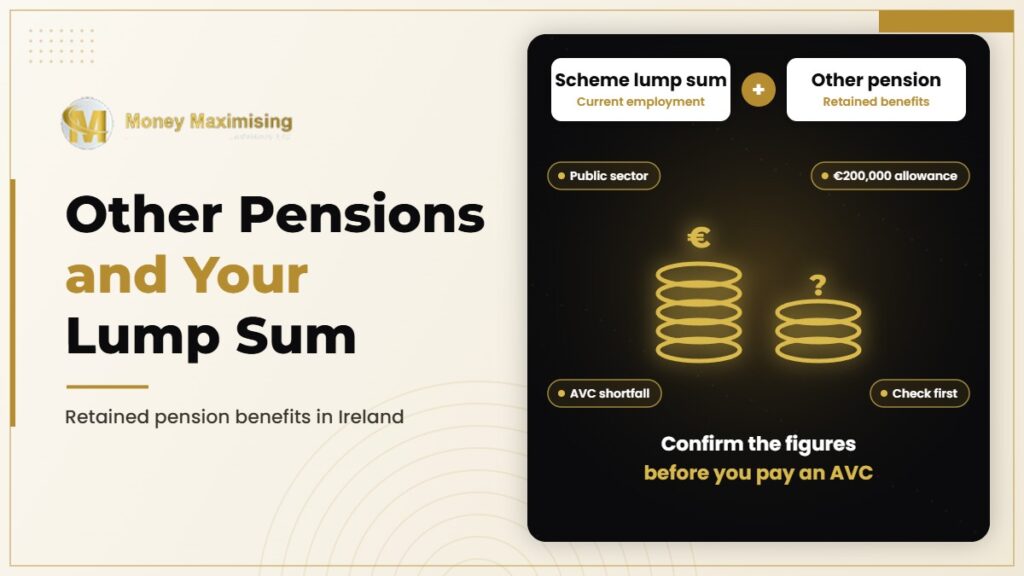
Start with the scheme lump sum and the applicable maximum under Revenue and scheme rules. Check whether other pension rights affect the calculation and review the separate lifetime tax-free allowance. Then allow for existing AVCs and any contributions already planned.
The resulting gap is not the same as the maximum contribution that could qualify for relief. Tax relief has its own age-related and earnings limits, and an AVC’s investment value can rise or fall. Ask for a calculation that separates the gross contribution, any estimated tax relief and the remaining cash target.
Keep the tax-relief paperwork separate
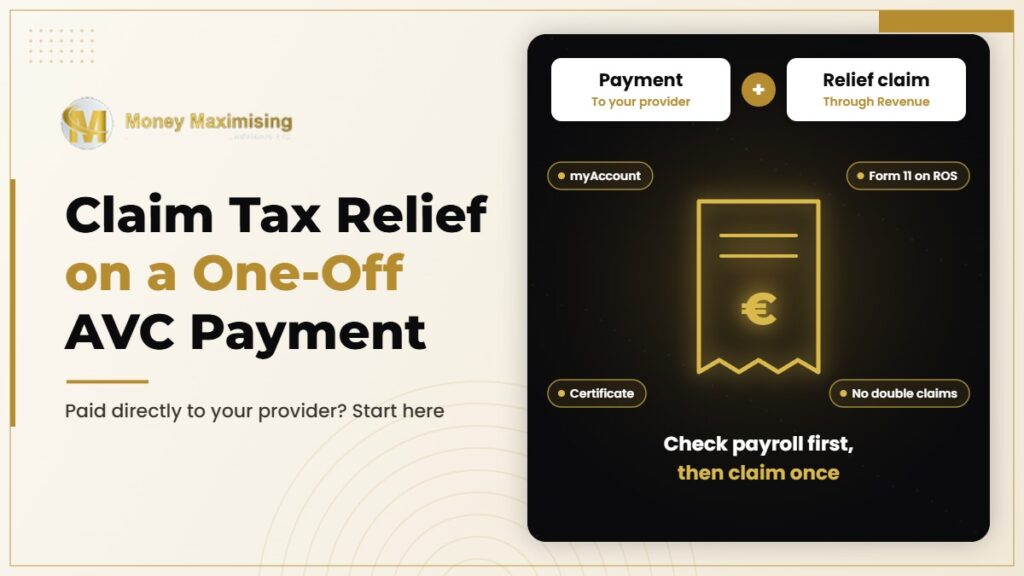
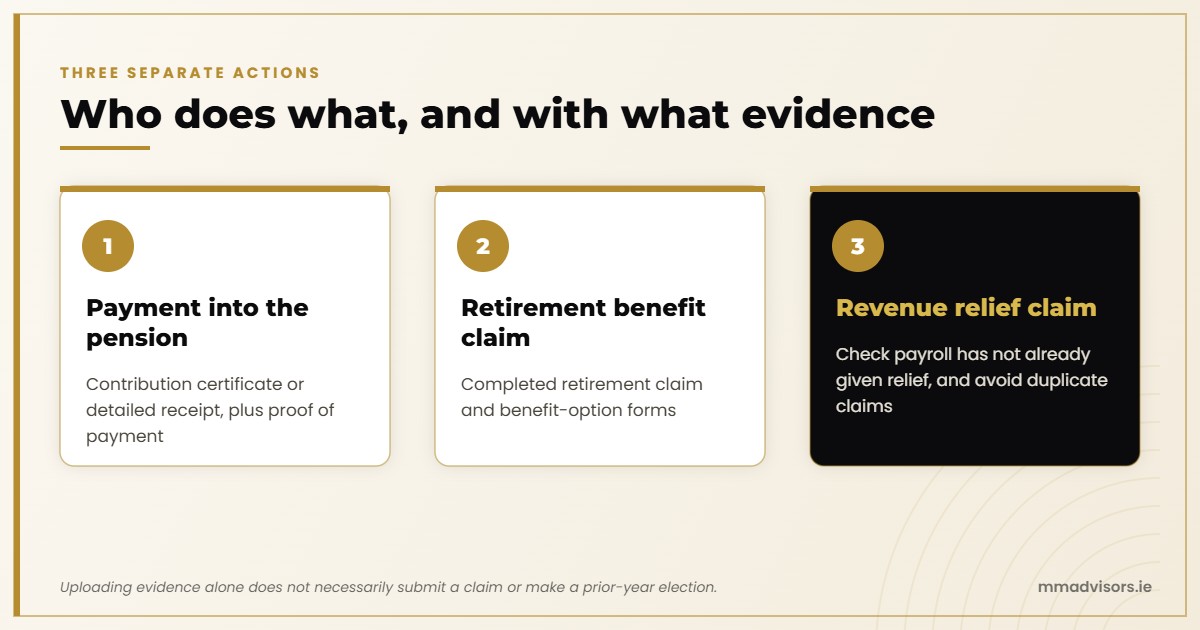
Ask the provider for a contribution certificate or detailed receipt and keep proof of payment. If you claim relief yourself, check whether payroll has already given relief for the same contribution. Do not submit a duplicate claim.
Payment into the pension arrangement, the retirement benefit claim and the Revenue relief claim are separate actions. Confirm who is responsible for each step and what evidence is needed. Uploading evidence alone does not necessarily submit a claim or make a prior-year election.
Your pre-payment checklist
- Retirement date and scheme membership confirmed.
- Employer pension and lump-sum quotation requested or received.
- Other pension benefits and any retained-benefits adjustment checked.
- Existing AVC valuation and planned contributions included.
- Provider confirms payment instructions, fees, cut-off date and forms.
- Eligible Income Tax relief and evidence requirements understood.
- Enough cash remains available to pay the gross contribution without relying on an assumed refund.
Frequently asked questions
When should I contact my AVC provider?
As soon as your retirement date is known. Ask for the provider-specific checklist and written deadlines.
Will my AVC and employer lump sum arrive on the same day?
Not necessarily. Ask the provider and scheme administrator who pays each benefit, by what method and when.
Can I pay an AVC on the tax deadline and still retire on time?
Do not assume so. A tax deadline does not override provider or retirement-processing requirements.
What if my final pension figures are not ready?
Ask the administrator which figures can be confirmed now and when final figures will be available. Avoid treating an estimate as a confirmed entitlement.
Related guides
- Public Sector AVCs: for the shortfall calculation and product context.
- Last Minute AVC: our Last Minute AVC service.
- Approaching retirement financial planning: for wider retirement preparation.
Sources
Money Maximising Advisors Ltd is regulated by the Central Bank of Ireland. C154250.