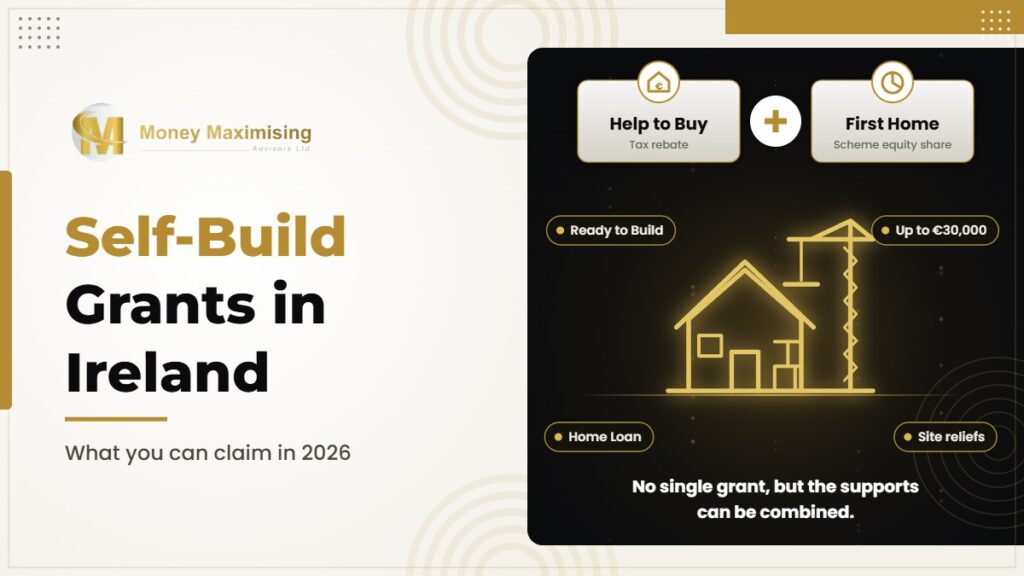
Building your first home is one of the few routes where first time buyers get dedicated State support even without buying from a developer. But the rules for self-builders differ from those for new estate homes, and getting the order wrong can cost you the full FTB grant.
This guide explains every first time buyers grant Ireland offers for a self-build, who qualifies, how to claim, and how the numbers work in practice. For a broader look at all supports, including discounted council sites and family site reliefs, see our guide to self-build grants in Ireland.
In this guide
Who Counts as a First Time Buyer for a Self-Build?
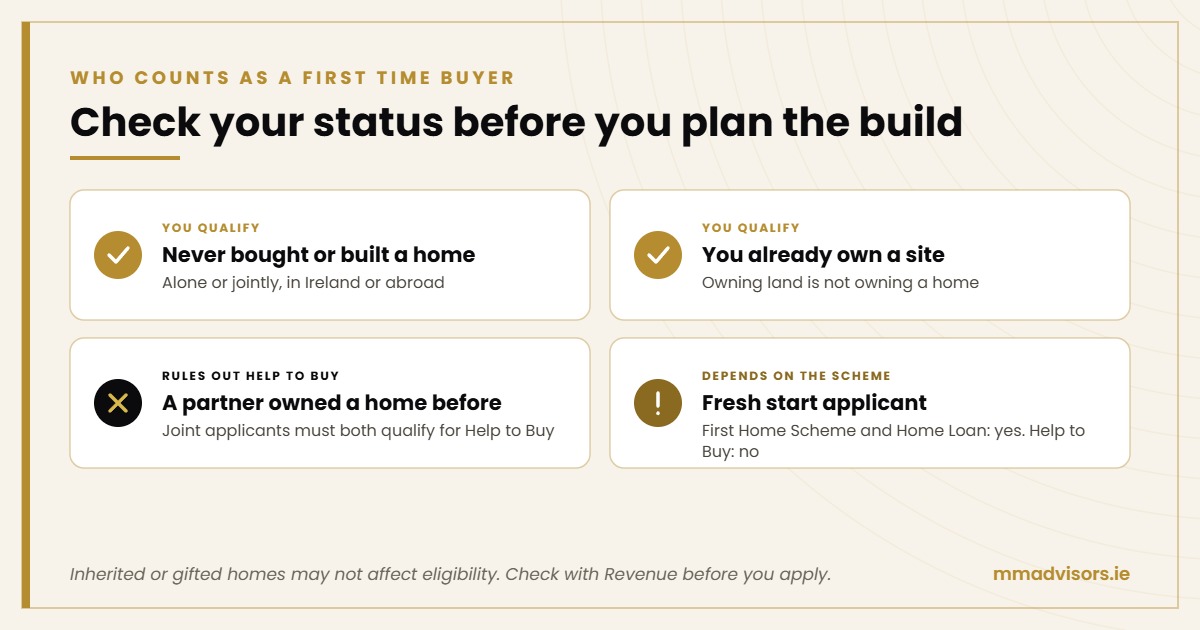
For Help to Buy, Revenue treats you as a first time buyer if you have never bought or built a house or apartment, alone or jointly, in Ireland or abroad.
Help to Buy: The Main First Time Buyers Grant for Self-Build
Help to Buy is a refund of income tax and DIRT, not a loan. For a self-build, you receive the lowest of:
- ✓30,000 euro
- ✓10% of the approved valuation, which is your site value plus the estimated build cost
- ✓The income tax and DIRT you paid over the previous four tax years
To qualify, the approved valuation must be 500,000 euro or less, your mortgage must be at least 70% of that valuation, and you must live in the home for five years. You do not need a Revenue approved contractor, but a solicitor registered with Revenue as a Help to Buy approver must verify your claim. The scheme runs until 31 December 2029.
How to claim Help to Buy on a self-build
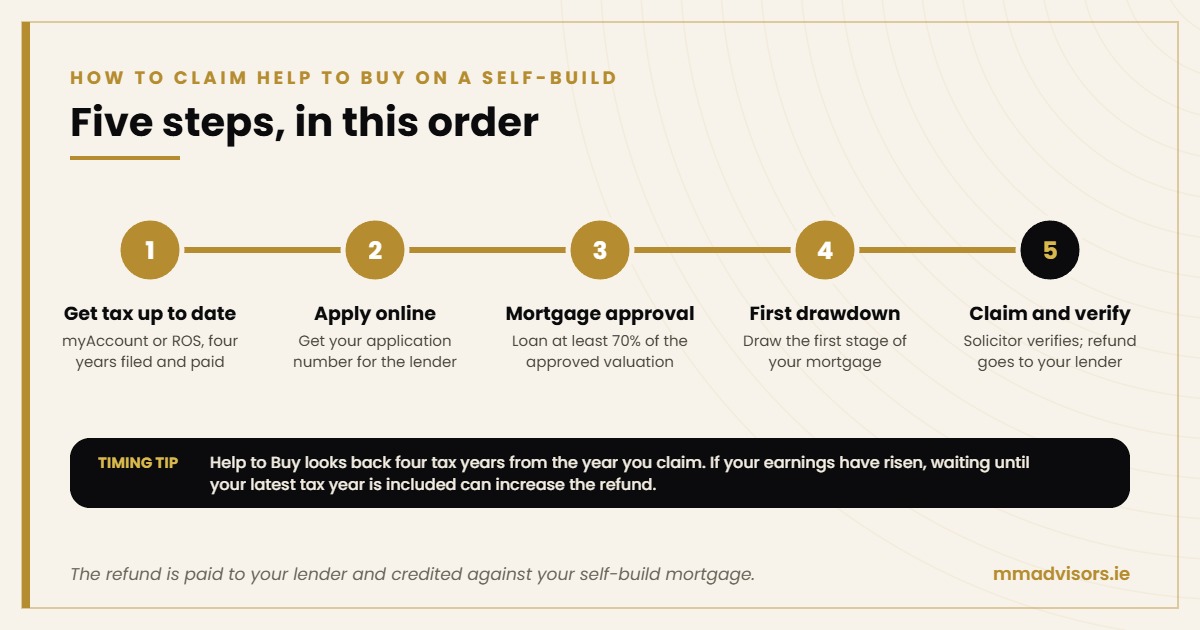
Timing matters
Help to Buy looks back four tax years from the year you claim, so if your earnings have risen, waiting until your latest tax year is included can increase your refund. Self-employed applicants should read our guide to the self-employed self-build mortgage, as unfiled returns are the most common reason a claim stalls.
First Home Scheme for First Time Self-Builders
The First Home Scheme is a shared equity scheme for first time buyers and fresh start applicants. It funds up to 30% of your certified build cost, or up to 20% if you also claim Help to Buy, in return for a share in your home.
Key rules for self-builders
- ✓You must borrow the maximum mortgage you qualify for
- ✓A certified build cost and certified valuation are required
- ✓Price ceilings apply by local authority area, with separate limits for self-builds
- ✓No charge for the first five years, then a service charge on any share you have not bought back
Not a grant
Model what buying back the equity share could cost as your home rises in value.
Local Authority Home Loan for First Time Self-Builders
The Local Authority Home Loan is a government backed mortgage for first time buyers and fresh start applicants who cannot borrow enough from a bank. It can fund a self-build and can be used with Help to Buy. Income limits and maximum loan amounts apply, so compare it against bank offers through independent mortgage comparison advice.
Worked Examples: How the Schemes Stack
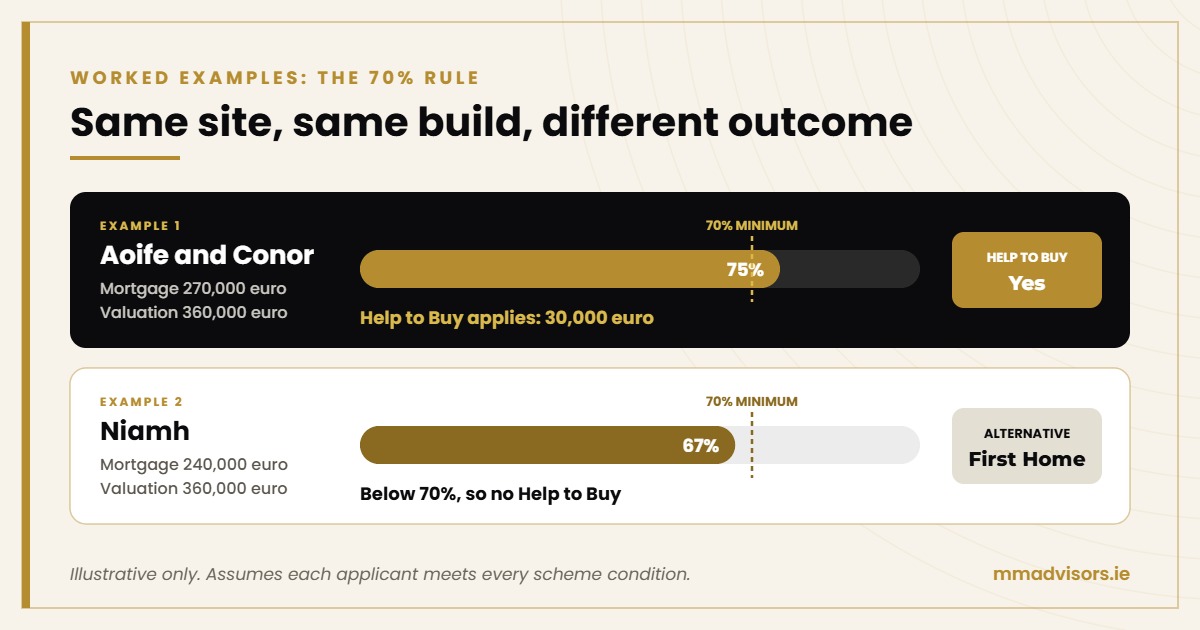
These examples are illustrative only and assume each applicant meets every scheme condition.
Example 1: Help to Buy works
Aoife and Conor own a site worth 60,000 euro and plan a 300,000 euro build, giving an approved valuation of 360,000 euro. Their combined income is 70,000 euro, so the 4 times income limit allows borrowing of up to 280,000 euro.
Example 2: The 70% trap
Niamh owns a site worth 60,000 euro and plans the same 300,000 euro build. Her income is 60,000 euro, so she can borrow up to 240,000 euro.
Alternatively, a smaller build or a lower specification could bring the valuation down so her mortgage clears 70%.
Plan early
This is why a first time buyer self-build mortgage needs planning before your architect finalises the design, not after.
Common Mistakes First Time Self-Builders Make
Budget for mortgage protection, which most lenders require before your first drawdown. If family are helping with your deposit, inheritance tax advice confirms how the gift is treated for capital acquisitions tax. Still building your savings? Our guide on how to save for a mortgage while renting covers practical steps.
How MM Advisors Helps First Time Self-Builders
As an independent mortgage broker, MM Advisors checks which first time buyers grant Ireland offers that you qualify for on a self-build, models your borrowing against the 70% rule before your plans are final, and sequences your Help to Buy, First Home Scheme and mortgage applications with a lender that suits your build. Learn more about our self-build mortgage service, or book a self-build mortgage consultation to review your figures.
First time self-builders
Check Your Figures Against the 70% Rule
Review your Help to Buy, First Home Scheme and mortgage plan before your design is final.