Searching for grants for self-build in Ireland can be confusing, because many of the supports are not grants at all. Some are tax rebates, some are equity shares you repay, and some are discounts on a site. This guide explains each scheme open to self-builders in 2026, who qualifies and how they fit alongside your self-build mortgage.
In this guide
What Grants Are Available for Self-Builds?
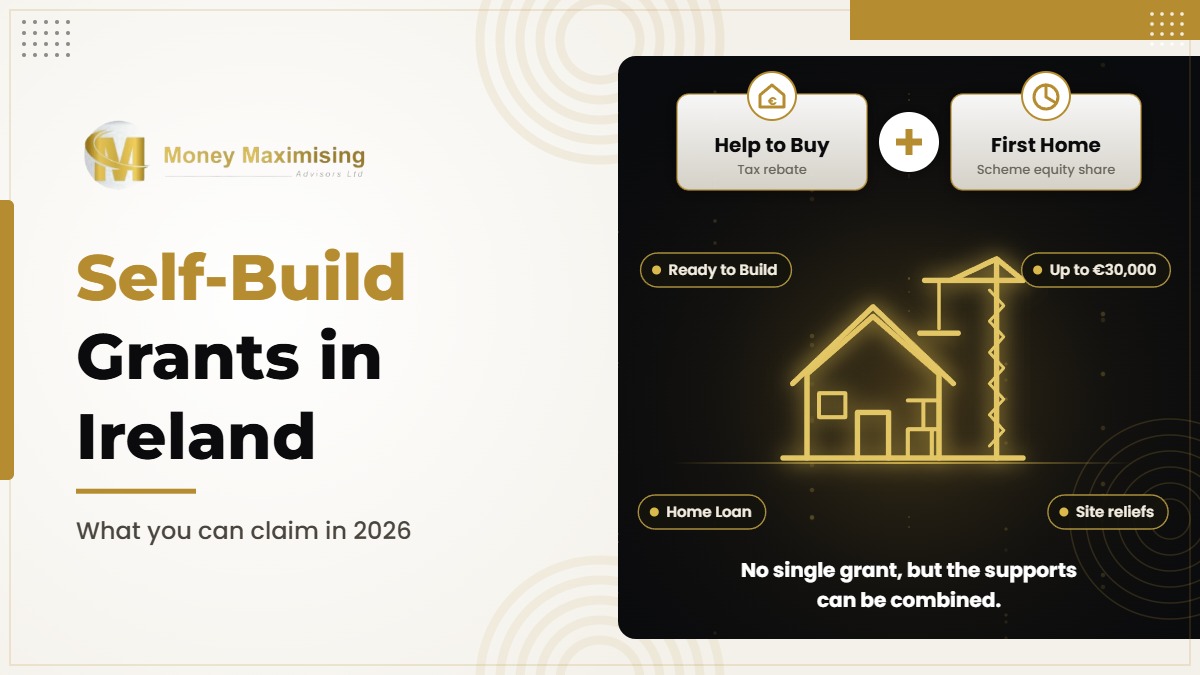
Five government supports can reduce the cost of building your own home in 2026, but only some of them are true grants. Knowing which is which matters, because equity shares and loans have to be repaid and discounts can be clawed back if conditions are broken.
Help to Buy
Rebate GrantFirst Home Scheme
Equity share RepayableReady to Build
Site discount GrantHome Loan
Loan RepayableFamily site reliefs
Tax relief SavingSelf-Build Government Grants at a Glance
| Scheme | What you get | Repayable? | Who it suits |
|---|---|---|---|
| Help to Buy | Tax rebate of up to 30,000 euro | No, if conditions are kept | People who have never owned a home, with Irish tax history |
| First Home Scheme | Equity share of up to 30% of build cost (20% with Help to Buy) | Yes, when you buy it back or sell | Self-builders short of funding |
| Ready to Build scheme | Up to 30,000 euro off a council serviced site | No, if you build and live there | Buyers without a site |
| Local Authority Home Loan | Government backed mortgage | Yes, it is a loan | Self-builders unable to borrow enough from a bank |
| Family site reliefs | Stamp duty exemption on a qualifying site transfer | No | Builders on family land |
Help to Buy for Self-Builders
Help to Buy is the largest true grant available to self-builders. It refunds income tax and DIRT you paid over the previous four years, up to the lowest of:
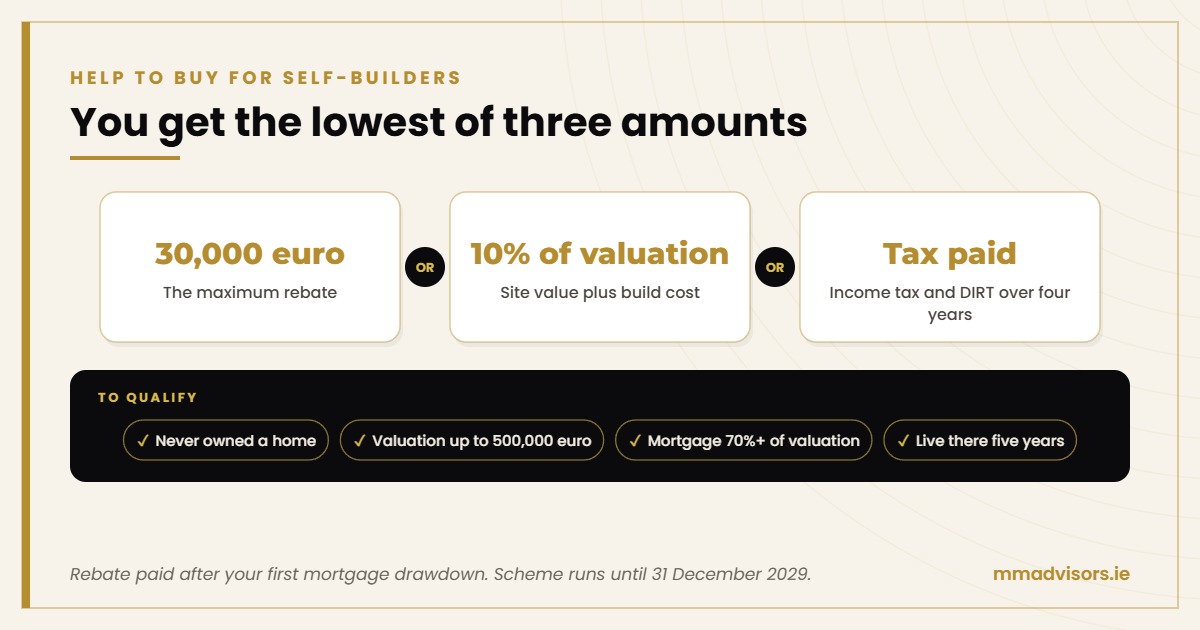
- ✓30,000 euro
- ✓10% of the approved valuation (site value plus build cost)
- ✓The tax you actually paid in those four years
To qualify you must never have owned a home, the approved valuation must be 500,000 euro or less, and your mortgage must be at least 70% of that valuation. You must live in the home as your main residence for five years. The rebate is paid after your first mortgage drawdown and the scheme runs until 31 December 2029.
Two traps that catch self-builders
Owning your site outright
If you own your site outright and borrow less than 70% of the valuation, you lose eligibility.
Self-employed tax returns
Every tax return for the four years must be filed and paid before you apply. Our guide to the self-employed self-build mortgage covers the tax compliance side in detail.
First Home Scheme for Self-Builders
The First Home Scheme is a shared equity scheme, not a grant. The State takes a share in your home in return for funding part of the build cost:
- ✓Up to 30% of the build cost, or up to 20% if you also claim Help to Buy
- ✓Minimum equity share of 2.5% or 10,000 euro, whichever is higher
- ✓Price ceilings apply by local authority area, with separate limits for self-builds
- ✓Participating lenders: AIB, EBS, Haven, Bank of Ireland and PTSB
Self-build applicants must provide a certified build cost and a certified valuation. There is no charge on the equity share for the first five years, after which a service charge applies on any share you have not bought back.
Model the long term cost
Because the share is linked to the home’s market value, it grows if your home rises in value. Model the long term cost before you commit, and make sure you have taken the maximum mortgage you qualify for, as the scheme requires this. Government funding for the scheme has been extended to at least June 2027.
Ready to Build Scheme: Discounted Serviced Sites
Under the Croí Cónaithe (Towns) Fund, councils sell serviced sites in towns and villages to individual self-builders at a discount of up to 30,000 euro on market value. The discount depends on what the council spent servicing the site with water, wastewater, power and access.
Key conditions
- ✓You can buy only one site under the scheme
- ✓The home must be your principal private residence
- ✓Councils set deadlines to apply for planning and complete the build
- ✓If you do not build, the discount must be repaid
Sites are released in small batches and advertised on council websites and in local newspapers, so check your local authority’s housing page regularly. If you are still saving for a site, our guide on how to save for a mortgage while renting covers practical strategies.
Local Authority Home Loan
The Local Authority Home Loan is a government backed mortgage for people who cannot get enough finance from a bank. It can be used for self-builds, and it can be combined with Help to Buy and, in many cases, the First Home Scheme.
A loan, not a grant
Income, property value and borrowing limits apply. Compare it against bank offers, as the right option depends on your income and build cost. Independent mortgage comparison advice shows both side by side.
Tax Reliefs When Building on Family Land
Many rural self-builders build on a site transferred by a parent. Two reliefs can save significant money:
Get inheritance tax advice before the transfer, as the order of transfer, planning and mortgage approval affects both reliefs. If you are buying a site on the open market instead, stamp duty applies to the purchase; see our guide to stamp duty for residential property in Ireland.
Supports That Have Closed or Do Not Apply to Self-Builds
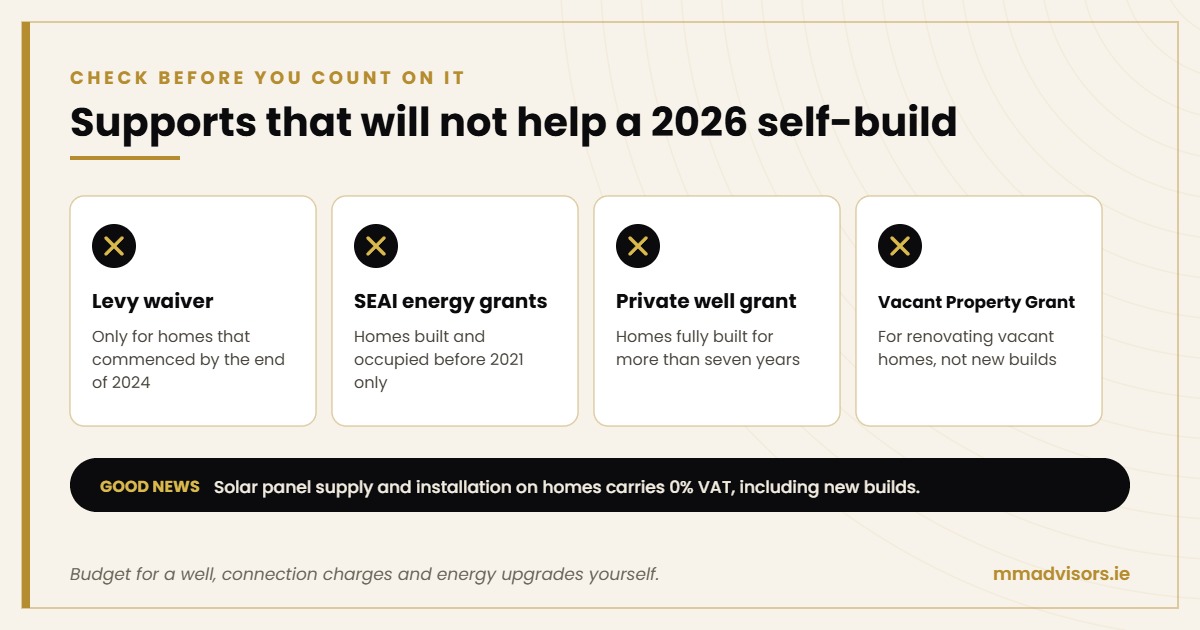
Several schemes appear in older guides but will not help a new self-build in 2026:
How to Combine Self-Build Supports
Many self-builders can stack Help to Buy, the First Home Scheme and a mortgage, with a council serviced site or family site as their contribution.
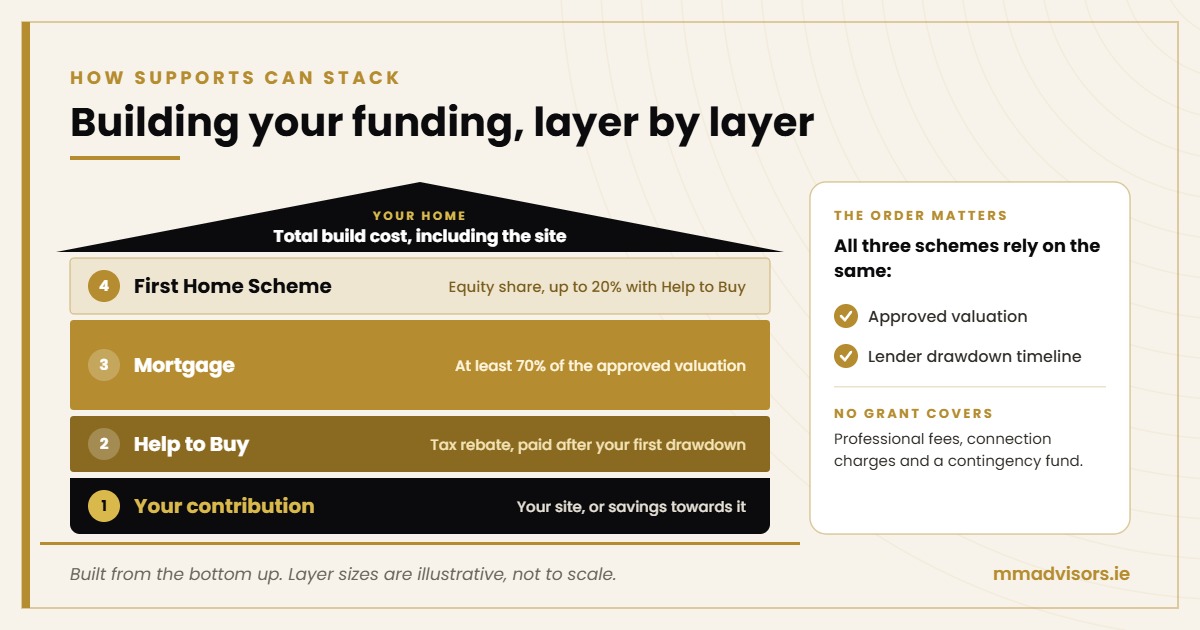
The order matters
Your mortgage approval, Help to Buy application and First Home Scheme eligibility certificate all depend on the same approved valuation, and must line up with your lender’s drawdown timeline.
Budget for what no grant covers
- ✓Professional fees, connection charges and a contingency fund
- ✓Mortgage protection, which most lenders require before your first drawdown
- ✓Cash between stage payments, where money management advice can help you plan
- ✓For returning emigrants, Help to Buy depends on Irish tax paid; our Irish ex-pat mortgages page explains your options
As an independent mortgage broker, MM Advisors checks which supports you qualify for, sequences your applications so nothing is lost, and matches you to a lender that accepts your build plan. See all our mortgages, or book a self-build mortgage consultation to review your funding plan before you start.
Self-build mortgages
Check Which Supports You Qualify For
Review your funding plan with an independent mortgage broker before you start building.