AVCS | EMPLOYEES WITH RENTAL INCOME | TAX DEADLINE 2026
Quick answer
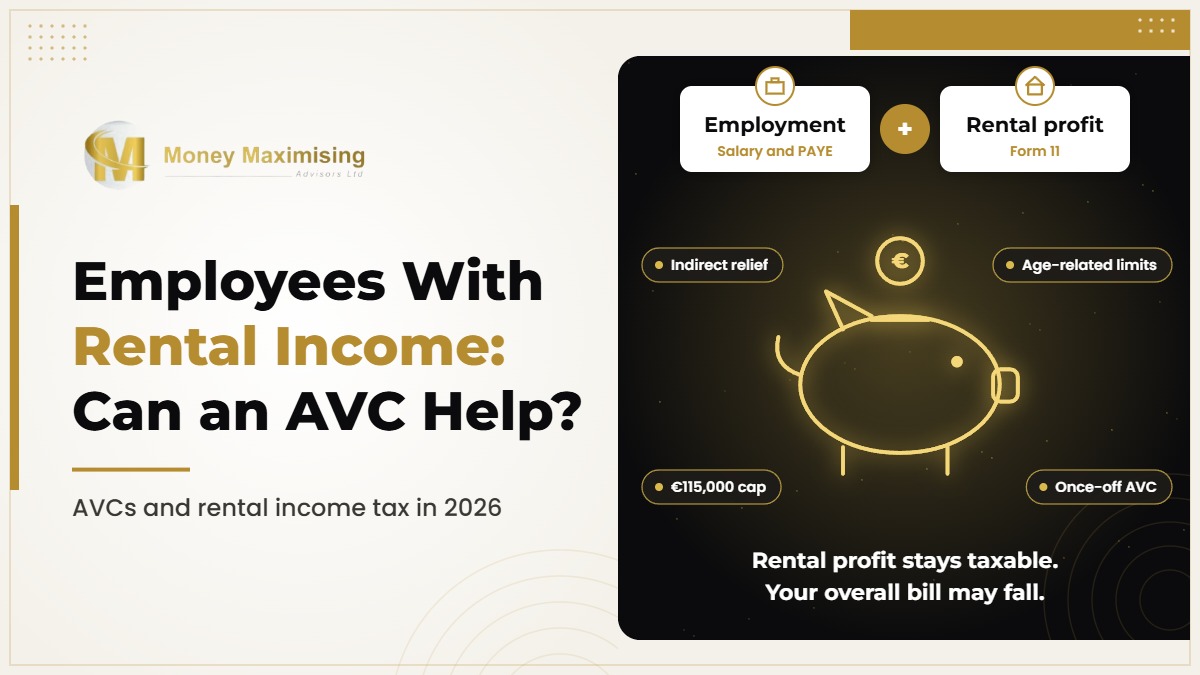
If you are an employee with one or more rental properties, the Form 11 balance can come as an unwelcome surprise. A qualifying AVC may reduce your overall Income Tax bill, even though it is not a deduction from rental profit.
The important distinction: direct versus indirect relief
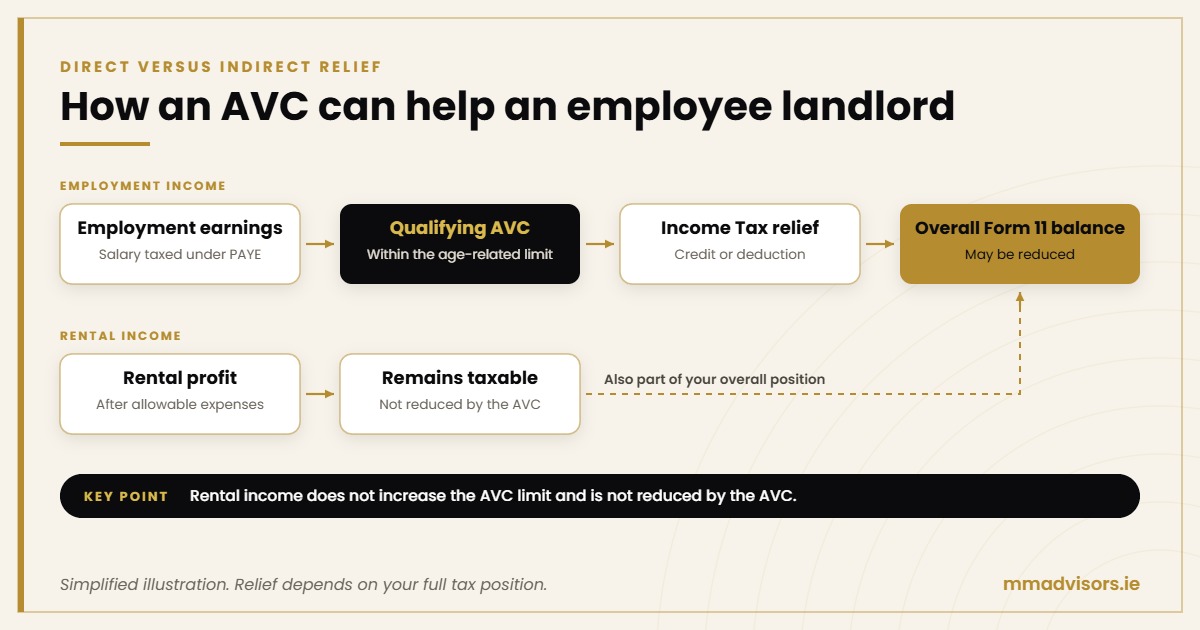
An Additional Voluntary Contribution is linked to earnings from the employment and the pension arrangement connected with that employment. Rental income does not become pensionable earnings, does not increase the AVC limit and is not reduced by the AVC.
However, Income Tax is assessed across the individual’s overall position. If PAYE has already been deducted from salary, a qualifying AVC claim can create an additional Income Tax credit or deduction. That relief may reduce the Form 11 balance that arose because of rental profit. This is why an AVC can indirectly help with the overall tax bill.
A useful planning question
Do not ask only, “How much tax is due on my rental income?” Also ask, “Do I have unused pension contribution capacity from my employment that could reduce my overall Income Tax liability?”
Why this is especially relevant to public-sector employees
Public servants commonly have pensionable employment income and may also own residential investment properties. Their main public-service pension contributions, existing AVCs and other personal contributions can use part of the annual tax-relief limit, but unused capacity may remain.
A properly structured once-off AVC can increase retirement benefits while reducing Income Tax. The available amount depends on age, eligible employment earnings, existing contributions, scheme membership and individual circumstances. Public-sector pension rules and projected benefits should also be reviewed before making a large contribution.
The age-related pension contribution limits
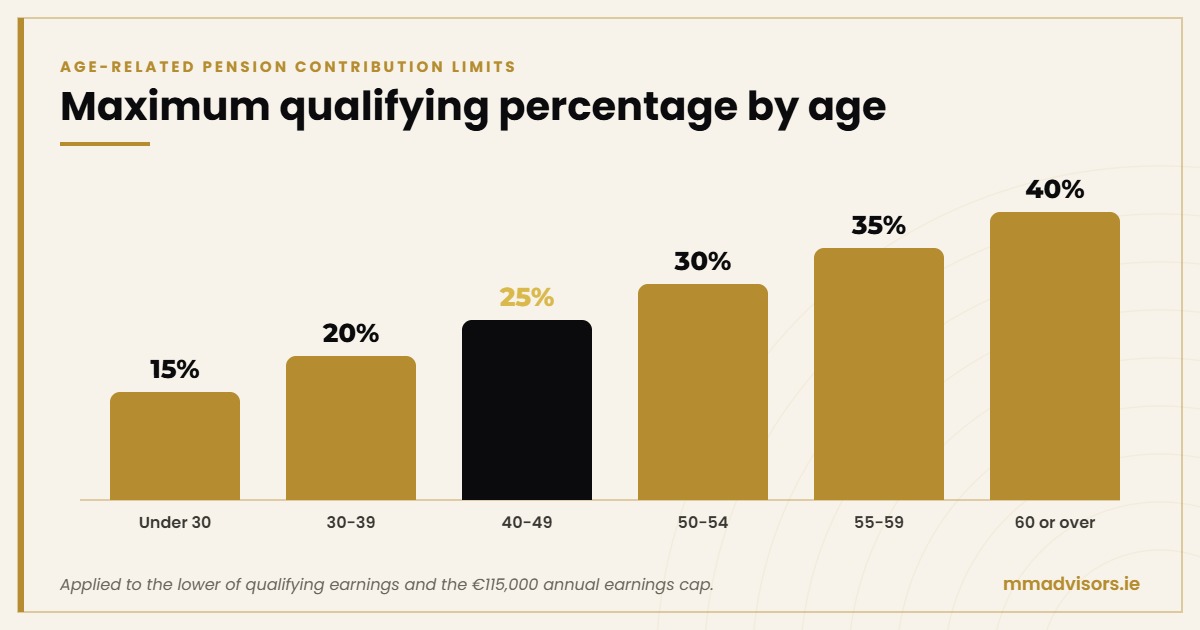
The percentage is applied to the lower of your qualifying earnings and the annual earnings cap of €115,000. Existing personal or employee pension contributions can use part of the available allowance.
| Age at end of tax year | Maximum qualifying percentage |
|---|---|
| Under 30 | 15% |
| 30-39 | 20% |
| 40-49 | 25% |
| 50-54 | 30% |
| 55-59 | 35% |
| 60 or over | 40% |
Worked example: public-sector employee with rental income
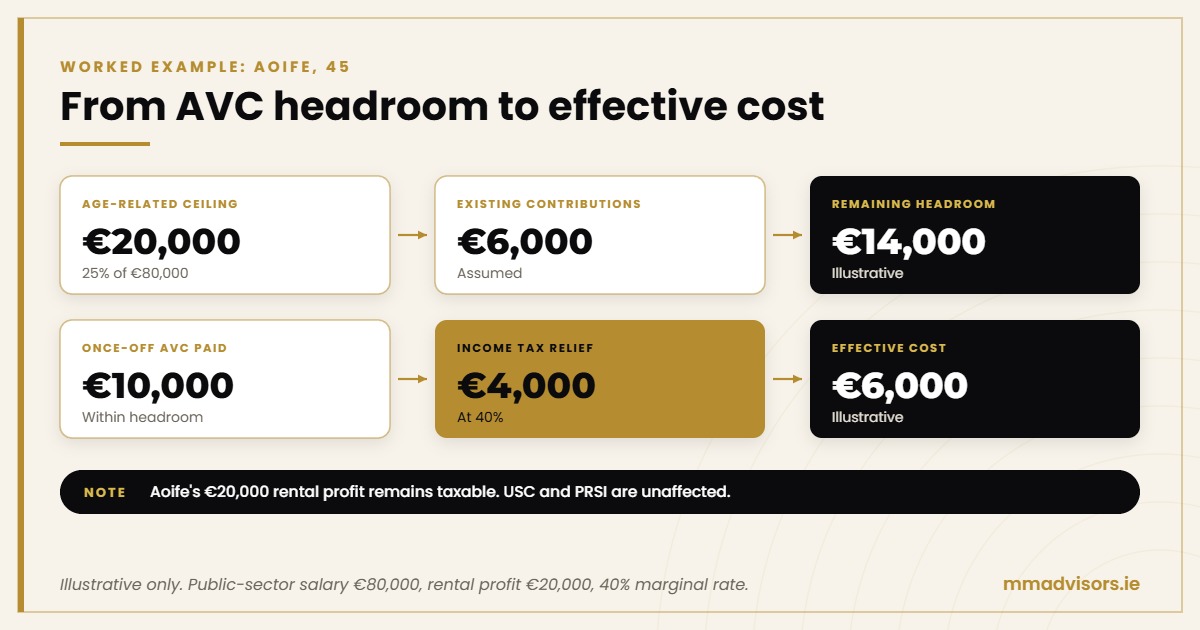
Aoife is 45, earns a public-sector salary of €80,000 and has net taxable rental profit of €20,000. She pays Income Tax at the 40% marginal rate. Her existing employee pension contributions for the year are assumed to be €6,000.
| Eligible employment earnings | €80,000 |
| Age-related ceiling at 25% | €20,000 |
| Less existing employee contributions | €6,000 |
| Illustrative remaining AVC headroom | €14,000 |
| Once-off AVC paid | €10,000 |
| Potential Income Tax relief at 40% | €4,000 |
| Illustrative effective cost of the AVC | €6,000 |
Aoife’s €20,000 rental profit remains taxable. The €4,000 relief arises from her qualifying employment earnings and may reduce her overall Form 11 Income Tax balance. USC and PRSI are unaffected.
What the example does – and does not – mean
- The rental profit is still €20,000 and remains subject to the applicable taxes.
- The AVC does not create an expense in the rental accounts.
- The tax-relief limit is calculated using Aoife’s employment income, not her rental income.
- The Income Tax relief may reduce her overall balance payable or create a refund, depending on PAYE already deducted and her complete tax position.
- The assumed €6,000 of existing contributions is illustrative. Actual public-sector deductions and tax-relief treatment must be checked.
Ready to speak with an advisor?
Or
Call us now (9am to 5pm, Mon to Fri)
Can a once-off AVC be claimed for the previous year?
Revenue permits a qualifying contribution paid after the end of a tax year, but before the following filing deadline, to be elected back to the earlier year. The contribution and election must be completed within the applicable deadline. For the 2025 return, the standard deadline is 31 October 2026, with an extension to 18 November 2026 for qualifying ROS pay-and-file users.
Because provider documentation, payroll information and scheme calculations can take time, employees should begin the process well before the deadline.
How AVC relief is claimed on Form 11
Revenue’s Form 11 guidance directs taxpayers to enter AVC relief through the PAYE/BIK/Pensions panel. The contribution certificate, policy details and employment information should be retained. Employees should coordinate the pension claim with their accountant or tax adviser so it is reflected correctly in the overall return.
Other planning points for employee landlords
- Confirm the rental profit after allowable rental expenses; do not use gross rent as the taxable figure.
- Check whether preliminary tax is also due for the current year.
- Review all employee and AVC contributions before calculating the available limit.
- Make sure the AVC is compatible with the occupational or public-sector scheme and retirement plan.
- Do not use cash needed for tax, property repairs, vacancies or personal emergencies.
- Compare pension charges, investment risk and expected access date before contributing.
Frequently asked questions
Can I deduct an AVC from rental income?
No. An AVC is not a rental expense and does not reduce taxable rental profit. The relief relates to qualifying earnings from the relevant employment.
Can the AVC still reduce the amount I pay with Form 11?
Potentially, yes. The Income Tax relief forms part of your overall tax calculation and may reduce the balance payable after PAYE credits and other items are included.
Does rental income increase my AVC limit?
No. The limit for an AVC connected to an employment is based on eligible earnings from that employment, subject to the age-related percentage and €115,000 earnings cap.
Do my normal public-sector pension contributions count?
Employee pension contributions and existing AVCs generally use part of the tax-relievable percentage limit. The exact calculation should be completed using your scheme and payroll information.
Does the AVC reduce USC or PRSI?
No. Employee pension contribution relief applies to Income Tax, not USC or PRSI.
Where do I claim AVC relief on Form 11?
Revenue directs AVC claims to the PAYE/BIK/Pensions panel. A PRSA or RAC that is not an AVC is generally entered through the Charges and Deductions panel.
Free initial consultation
Have employment income and rental property?
Book a free initial consultation with Money Maximising Advisors. We can review your public or private-sector pension, estimate the available AVC capacity and illustrate how a contribution may affect your overall tax bill.
Sources and important information
Revenue guidance accessed September 2026:
Important: This article is general information, not tax, legal or investment advice. Tax relief depends on individual circumstances, Revenue rules and limits. Tax treatment may change. Pension investments can fall as well as rise, and retirement access rules apply.
Money Maximising Advisors Limited | Central Bank of Ireland C154250 | 091 393 125 | office@mmadvisors.ie