PENSIONS | SOLE TRADERS | FORM 11 GUIDE 2026
Quick answer
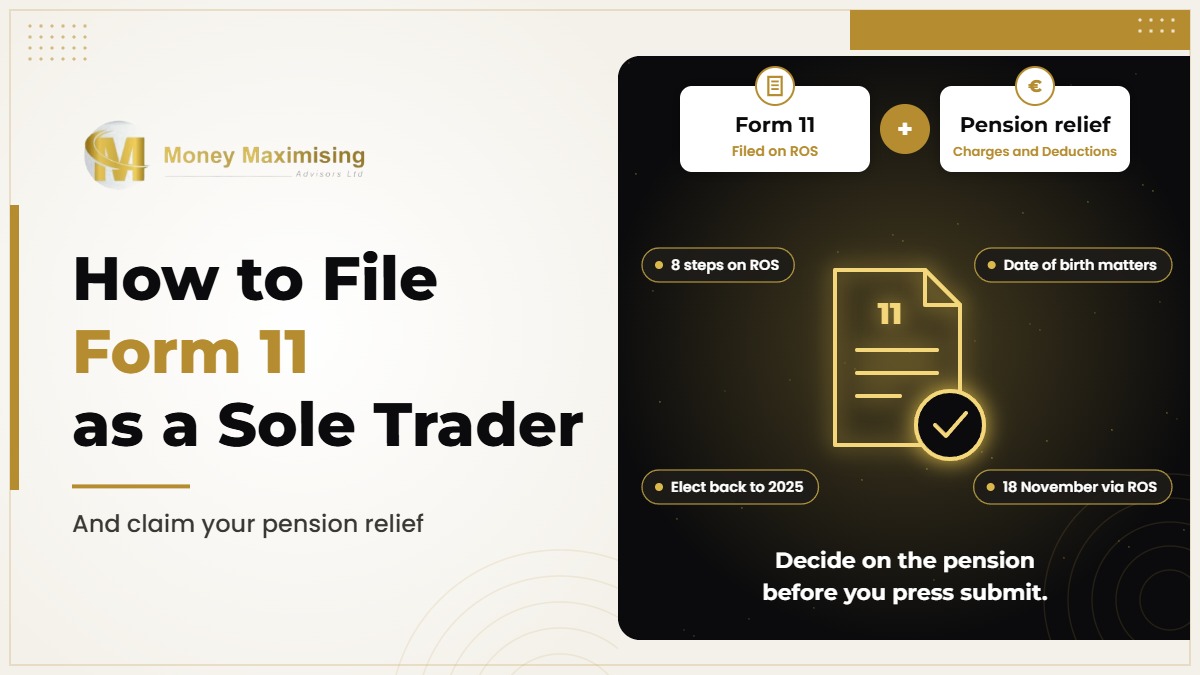
Filing Form 11 is not just about reporting your profit. It is also the one place a sole trader claims tax relief on pension contributions, including a contribution paid now and elected back to 2025. Here is the step-by-step process, with the pension claim built in.
Know the deadline first
Form 11 for the 2025 tax year, together with the balance of 2025 tax and preliminary tax for 2026, is due by Saturday 31 October 2026. If you both file and pay through the Revenue Online Service (ROS), the date is extended to Wednesday 18 November 2026. If only one of those is done through ROS, the extension does not apply.
Why the pension question belongs here
A qualifying pension contribution paid after 31 December 2025, but on or before your filing date, can be elected back against 2025 income on the return itself. Once the return is filed and the deadline passes, that option for 2025 is gone. Decide on the pension before you press submit, not after.
Before you start: what you need
- ROS access – registration for Income Tax and a ROS digital certificate. New users receive a ROS access number by post, so apply well ahead of the deadline.
- Trading figures for 2025 – turnover, allowable expenses by category, and capital allowances on equipment or vehicles.
- Other income – PAYE employment, rental profit, deposit interest or dividends. These are assessed together with your trade.
- Payments already made – preliminary tax paid for 2025 and any tax deducted at source, such as professional services withholding tax.
- Pension paperwork – contribution certificates for any PRSA or personal pension paid in 2025, and for any contribution you plan to make before the deadline.
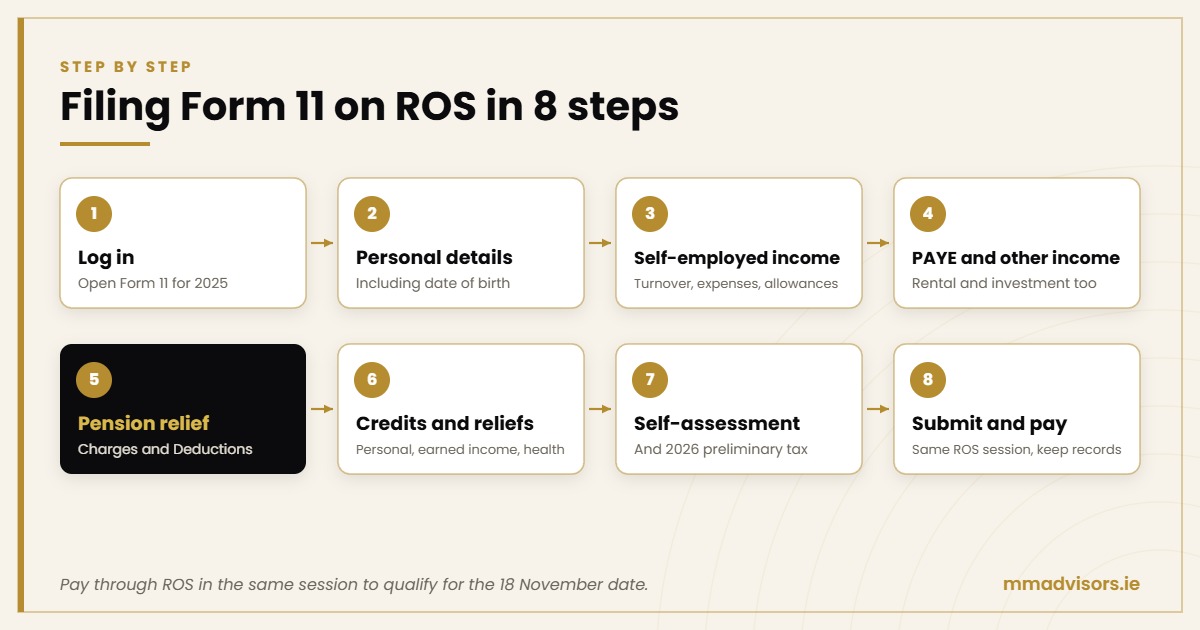
Step by step: filing Form 11 on ROS
- Log in and open Form 11 for 2025
Sign in to ROS, go to File a Return, select Income Tax and Form 11 for 2025. Choose the pre-populated version if you also have PAYE income, so employment pay and tax already deducted are carried in. - Complete Personal Details, including date of birth
Revenue uses your date of birth to apply the correct age-related pension limit. If it is missing or wrong, your pension relief may be restricted. - Enter your self-employed income
Complete the trade panel and the extracts from your accounts: turnover, expenses and capital allowances. ROS uses these to arrive at your taxable trading profit. - Add PAYE and other income
If you had a job during 2025, confirm the PAYE figures. Add rental and investment income in their own panels. Everything is taxed together, so do not treat the trade in isolation. - Claim pension relief in Charges and Deductions
Enter PRSA and retirement annuity (personal pension) contributions here. Include contributions paid during 2025 and any contribution paid in 2026, before your filing date, that you are electing to treat as paid in 2025. - Claim credits and other reliefs
Check personal and earned income credits, health expenses and any other reliefs that apply to you. - Complete the self-assessment and preliminary tax
Run the IT Self-Assessment panel, review the calculation, then enter 2026 preliminary tax and complete the Statement of Net Liabilities. - Submit, pay and keep records
Sign and submit the return, then pay through ROS in the same session to qualify for the 18 November date. Keep the acknowledgement, workings and pension certificates for at least six years.
Where pension contributions go on Form 11
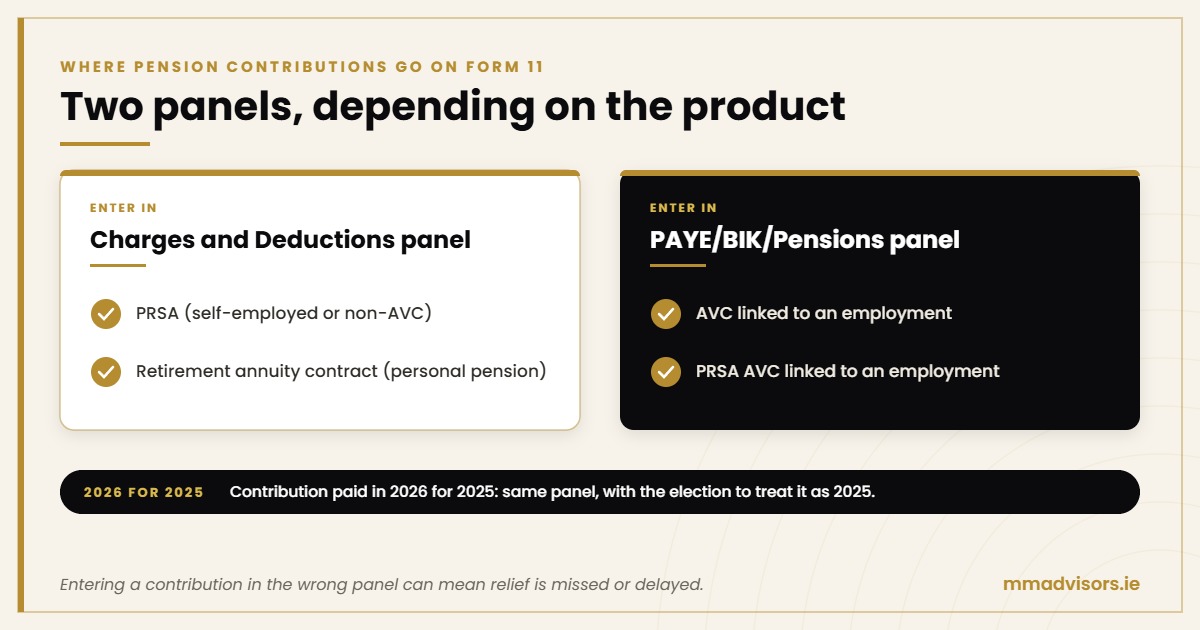
Different pension products are claimed in different parts of the return. Entering a contribution in the wrong panel is one of the most common reasons relief is missed or delayed.
| Type of contribution | Where to enter it |
|---|---|
| PRSA (self-employed or non-AVC) | Charges and Deductions panel |
| Retirement annuity contract (personal pension) | Charges and Deductions panel |
| AVC or PRSA AVC linked to an employment | PAYE/BIK/Pensions panel |
| Contribution paid in 2026 for 2025 | Same panel, with the election to treat it as 2025 |
How much can a sole trader claim?
Relief is limited by age and by net relevant earnings, broadly your taxable profit from the trade after capital allowances and losses. The percentage applies to the lower of those earnings and the €115,000 annual earnings limit. Relief is given against Income Tax at your marginal rate; it does not reduce USC or PRSI.
The age-related pension contribution limits
| Age at end of tax year | Maximum qualifying percentage |
|---|---|
| Under 30 | 15% |
| 30-39 | 20% |
| 40-49 | 25% |
| 50-54 | 30% |
| 55-59 | 35% |
| 60 or over | 40% |
Worked example: filing with a pension claim
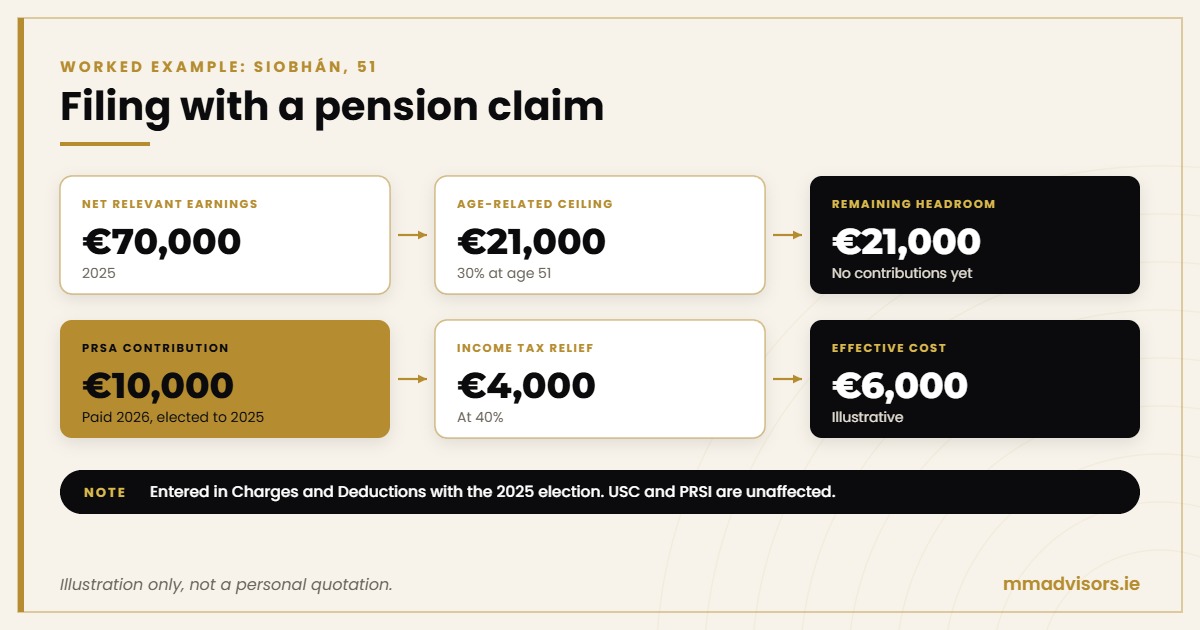
Siobhán is 51 and runs a design business as a sole trader. Her net relevant earnings for 2025 were €70,000, with a substantial portion taxed at 40%. She made no pension contributions during 2025. Before filing in November 2026, she pays into a PRSA and elects to treat it as paid in 2025.
| Net relevant earnings for 2025 | €70,000 |
| Age-related ceiling at 30% | €21,000 |
| Less contributions already made for 2025 | €0 |
| Illustrative remaining headroom | €21,000 |
| PRSA contribution paid in 2026, elected to 2025 | €10,000 |
| Potential Income Tax relief at 40% | €4,000 |
| Illustrative effective cost of the contribution | €6,000 |
Siobhán enters the €10,000 in the Charges and Deductions panel with the 2025 election. Her 2025 Income Tax falls by up to €4,000. If her 2026 preliminary tax is based on 100% of her 2025 liability, that figure may also fall. USC and PRSI are unaffected.
Ready to speak with an advisor?
Or
Call us now (9am to 5pm, Mon to Fri)
Common Form 11 mistakes sole traders make
- Leaving ROS registration until the last week and missing the extended deadline.
- Entering gross income instead of profit after allowable expenses and capital allowances.
- Forgetting PAYE income from a job held during the year, which pushes trading profit into the 40% band sooner.
- Putting a PRSA in the PAYE/BIK/Pensions panel, or an AVC in Charges and Deductions.
- Paying a pension contribution after filing and expecting it to count for 2025.
- Leaving out the date of birth, so the age-related limit is not applied correctly.
- Underestimating preliminary tax and facing interest later.
Do you need an adviser?
Many sole traders with tidy records file their own Form 11. An accountant is worth it when there are several income sources, capital allowances, losses or a large balance due. The pension decision is different: it is a long-term financial commitment as well as a tax decision, so product choice, charges, investment risk and retirement plans should be reviewed with a regulated adviser before a lump sum is paid.
Frequently asked questions
Can I claim pension relief on Form 11 for a contribution I make now?
Generally, yes. A qualifying contribution paid on or before your 2025 return filing date can be elected back to 2025 on the return. Confirm the applicable date with your adviser if you are relying on the ROS extension.
Which panel do I use for a PRSA?
A PRSA that is not an AVC is entered in the Charges and Deductions panel. AVCs, including PRSA AVCs linked to employment, go in the PAYE/BIK/Pensions panel.
Do I need to send the pension certificate to Revenue?
Not usually with the return, but keep it. Revenue can ask for evidence of the contribution, and records should be kept for at least six years.
Does pension relief reduce USC or PRSI?
No. Relief applies to Income Tax only.
I am a sole trader and an employee. Which limit applies?
Your limit depends on the earnings the pension is connected to. Trading profit supports a personal PRSA or retirement annuity; employment earnings support AVCs. An adviser can map out the headroom across both.
What happens if I file late?
A late return attracts a surcharge of 5% of the liability (up to €12,695) within two months, or 10% (up to €63,485) after that, plus interest on late payment. The chance to elect a contribution back to 2025 is also lost.
Before you submit
Filing Form 11 as a sole trader?
Find out your pension headroom and how a contribution elected back to 2025 may affect your bill.
Sources and important information
Important: This article is general information, not tax, legal or investment advice. Tax relief depends on individual circumstances, Revenue rules and limits. Tax treatment may change. Pension investments can fall as well as rise, and retirement access rules apply.
Money Maximising Advisors Limited | Central Bank of Ireland C154250 | 091 393 125 | office@mmadvisors.ie