Most people compare car insurance quotes by looking at one number. That is how you end up with a policy that is thirty euro cheaper and five hundred euro worse when you claim. Two quotes within a few euro of each other can carry different excesses, different exclusions and a different level of protection entirely.
This guide covers what to line up against what, why Irish insurers quote so differently for the same driver, which factors you can actually influence, and the specific traps that make a cheap quote expensive later.
In this guide
- Information you need for a quote
- Why quotes differ so much
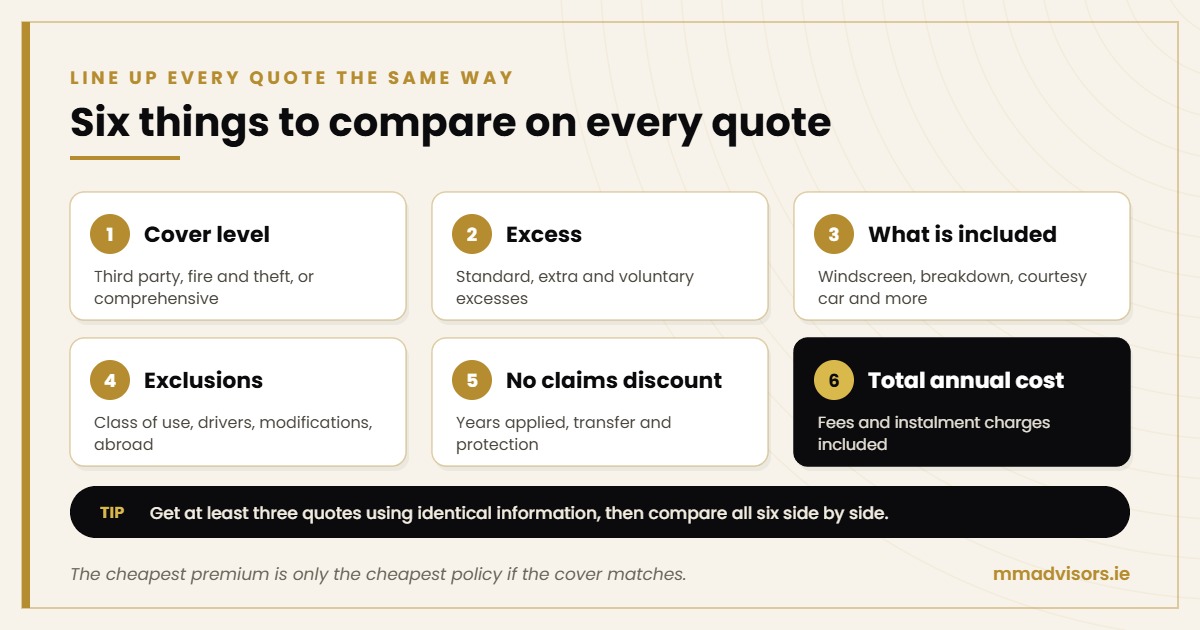
- Compare the same level of cover
- Check the excess
- What each policy includes
- Read the exclusions
- Your no claims discount
- Compare the total cost
- Broker, insurer or comparison site
- Quotes for your circumstances
- Telematics policies
- Never let cover lapse
- Check the quote before you buy
- Frequently asked questions
What information do you need to get a car insurance quote?
Have all of this in front of you before you start, because changing an answer halfway through means you are no longer comparing like for like.
About you
- ✓Full name, address and date of birth
- ✓Driving licence number and your Driver Number
- ✓Occupation
- ✓Years of driving experience and licence type
- ✓Penalty points, if any
- ✓Previous claims, including non fault claims
- ✓Your no claims discount, in years
About the car
- ✓Make, model, engine size and year
- ✓Registration number
- ✓Estimated value
- ✓Any modifications
- ✓Where it is parked overnight
About how you use it
- ✓Annual mileage, estimated honestly
- ✓Class of use, meaning social, social and commuting, or business
- ✓Any named drivers you want added, with their own Driver Numbers
The Driver Number catches people out
Since 31 March 2025, drivers taking out or renewing motor insurance in Ireland must provide their Driver Number, shown at section 4(d) of the driving licence, including the Driver Numbers of any named drivers. Have everyone’s licence to hand before you start, not halfway through the third quote.
Accuracy here is not a formality. An inaccurate mileage estimate, the wrong class of use, or an undeclared modification can affect whether a claim is paid. A quote built on wrong information is not a cheaper quote, it is an unreliable one.
Why do car insurance quotes differ so much between insurers?
Because every insurer is running a different model on the same facts, and the difference is often larger than anything you can negotiate.
Insurers price from their own claims experience. If one insurer has paid out heavily on a particular car, age band, county or occupation, its pricing for that profile goes up regardless of what you personally have done. Another insurer with a different claims book sees the same driver as ordinary business.
Appetite matters as much as risk. Some insurers actively want certain segments and price to win them. Others quote a deliberately unattractive price rather than decline outright. A high quote is sometimes a soft refusal.
What this means in practice
- ✓A difference of several hundred euro between insurers for the same driver and car is normal, not an error.
- ✓The cheapest insurer for you is not the cheapest insurer generally, and the ranking changes year to year.
- ✓Loyalty rarely earns the lowest price, so the cheapest quote this year may not be from last year’s insurer.
- ✓One quote tells you almost nothing, because you have no idea where it sits in the range.
This is the single strongest argument for comparing properly rather than renewing. Our guide to car insurance cost in Ireland sets out which factors do the most work in Irish motor pricing.
Ignore American advice on this
Credit scores do not feature in Irish motor insurance pricing the way they do in the United States. If you have read American advice about improving your credit score to lower your premium, it does not transfer. Nor do state minimum limits, since Ireland is a single jurisdiction with one statutory minimum.
Compare the same level of cover first
Before you compare any premium, confirm the two quotes are for the same product. There are three levels of motor cover in Ireland and they are not interchangeable.
Like for like
A comprehensive quote of 600 euro is not more expensive than a third party quote of 500 euro. They are different products. Comparing them on price alone is comparing nothing.
Is comprehensive cover worth it, or is third party enough?
Comprehensive is usually worth it unless the car is worth very little. The question to ask is what you would do if the car were written off tomorrow in an accident that was your own fault. If you could not replace it out of pocket, you need comprehensive.
Third party or third party, fire and theft can make sense for an older, low value car where the premium difference is large relative to what the insurer would ever pay out. Run both quotes and compare the gap against the car’s realistic value. On many modern cars the gap is small enough that comprehensive is the obvious choice.
Comprehensive also carries the extras that matter in practice: windscreen cover, courtesy car, and in some cases breakdown assistance. Those often matter more day to day than the headline cover level.
Check the excess on every quote
The excess is the amount you pay towards an eligible claim before the insurer pays the rest. It is the most common reason a cheap quote turns out not to be cheap.
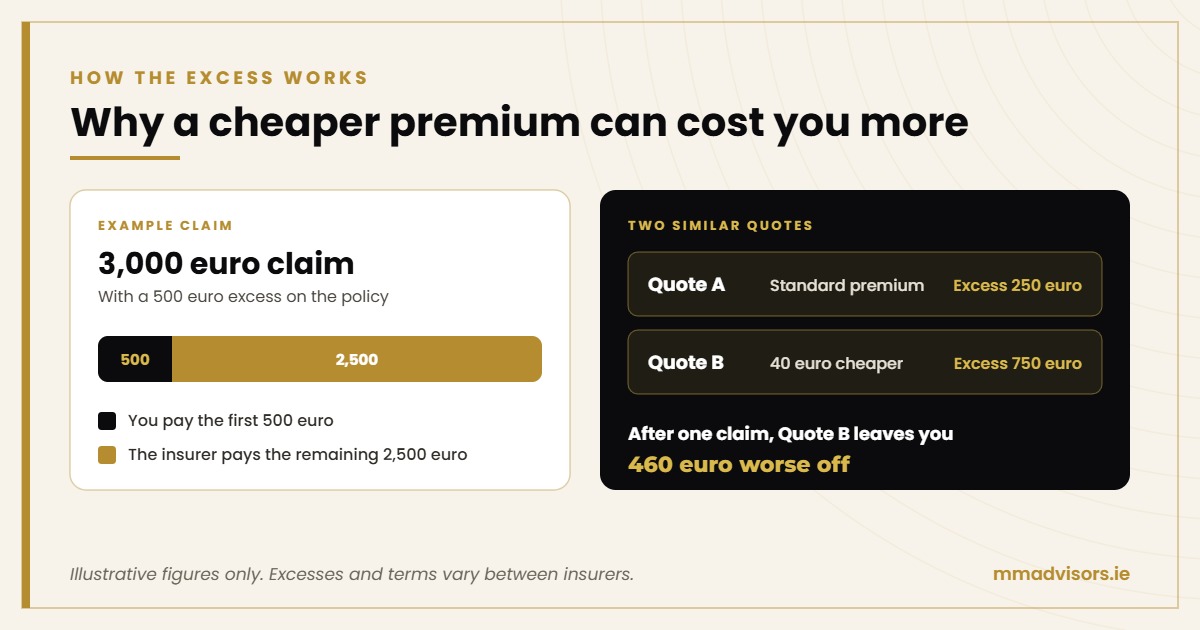
If your policy carries a 500 euro excess and you make an eligible claim for 3,000 euro, you pay the first 500 and the insurer pays the balance under the policy terms.
Three things to check on each quote
The standard excess
Record it next to the premium. Always.
Different excesses for different claims
Accidental damage, theft, fire and windscreen often carry separate figures. Some policies also apply an additional young driver or inexperienced driver excess, which can be substantial.
Whether a voluntary excess has been added
Some quotes look competitive because a voluntary excess is already built in. Raising the excess lowers the premium, which is a legitimate trade, but only if you could actually pay the figure. An excess you cannot afford is not a saving, it is a deferred problem.
Do the maths
A quote that is 40 euro cheaper with a 500 euro higher excess is a worse deal for anyone likely to claim once in the next few years.
Check what each policy actually includes
Two policies at similar prices can carry very different benefits. Depending on the insurer, these may be standard, optional or absent:
Do not simply pick the longest list. Work out which three or four of these you would actually use, then check the cost of adding them where they are not standard.
Someone driving sixty kilometres each way every day should weigh breakdown assistance heavily. Someone with a second car in the household barely needs a courtesy car. The right extras depend on how you actually drive, not on which list is longer.
Can I drive another car on my own comprehensive policy?
Not automatically. Driving other cars cover is an extension, not a standard feature, and it is included less often than people assume.
Where it is included, it usually applies only to the policyholder, only on third party cover rather than comprehensive, only with the owner’s permission, and only where the other car is itself insured. It frequently excludes drivers under a certain age.
Check your own certificate and schedule before driving anyone else’s car. If you regularly drive a family member’s vehicle, being added properly as a named driver is the reliable route, and our guide to named driver car insurance covers how that works.
Read the exclusions, not just the benefits
An exclusion is a circumstance where the insurer may not pay. Exclusions vary between policies far more than benefits do, and they are where declined claims come from. Check how each quote treats:
Where the real comparison happens
Two insurers may both advertise windscreen cover, and have completely different excesses, limits and repair conditions behind it. The policy document is where the real comparison happens.
How your no claims discount affects each quote
Your no claims discount, often shortened to NCD, is usually the largest single discount on an Irish motor policy, and it needs checking on every quote individually.
Confirm it has been applied correctly
Check the number of years on each quote matches what you actually hold. A quote built on the wrong NCD is not comparable.
Check it will be accepted
When switching insurer, confirm your existing NCD transfers and find out what proof is required. Most insurers want a renewal notice or a letter from the previous insurer, usually issued within the last two years.
Ask what protection costs and what it does
NCD protection lets you make a limited number of claims without losing your discount. It does not freeze your premium. A protected discount applied to a higher base rate still produces a higher bill.
Understand step back
Many policies reduce the discount by two years after a fault claim rather than wiping it. The exact step back varies and is worth comparing.
Our guide to the no claims bonus in Ireland covers how the discount builds, transfers and recovers after a claim, and car insurance claims in Ireland sets out what a claim does to your next renewal.
Compare the total cost, not the headline premium
The figure at the top of a quote is often not what you will pay over the year.
Paying monthly almost always costs more than paying annually, because the instalment arrangement carries interest or a finance charge. Two quotes with identical annual premiums can differ meaningfully once monthly costs are included.
Same basis, every time
Compare the total twelve month cost on the same payment basis across every quote. Comparing one insurer’s annual figure against another’s monthly deposit tells you nothing.
Where to get quotes: broker, insurer or comparison site
Each route reaches a different part of the market, and none reaches all of it.
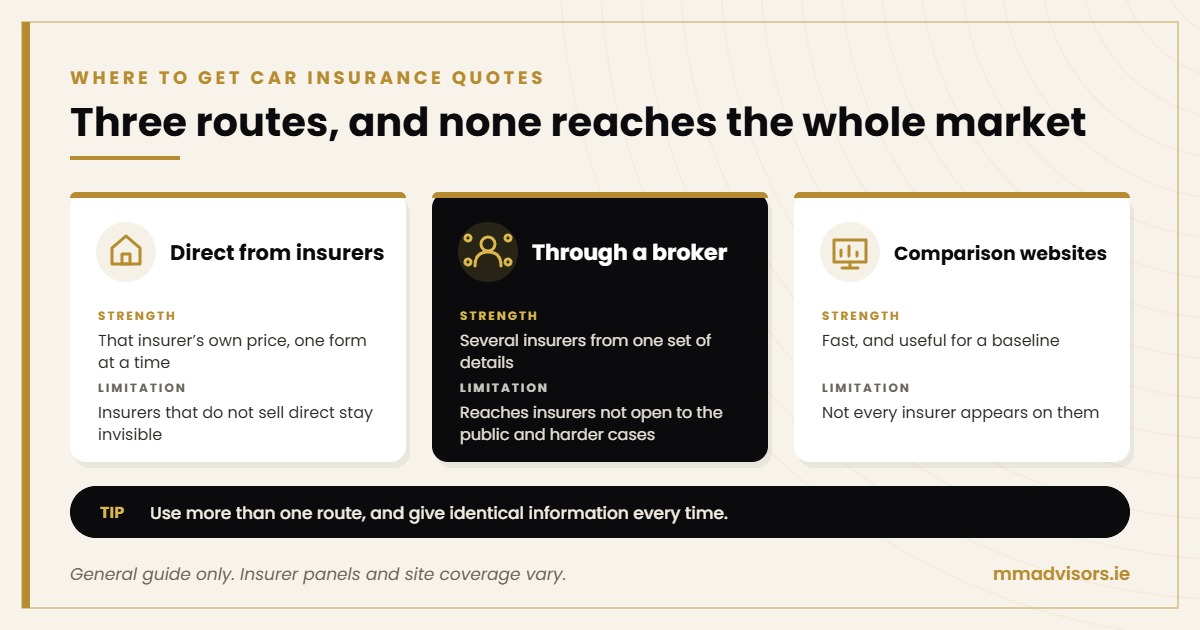
The practical approach is to use more than one route, and to give identical information every time. If you adjust your mileage, occupation, parking or cover level between quotes, you have stopped comparing.
Before you switch
It is also worth going back to your existing insurer with a competing quote before you switch. Sometimes they will move. Often they will not, which is itself useful information.
Comparing quotes for your specific circumstances
Standard quote forms assume a standard driver. If you are not one, the comparison looks different, and the cheapest mainstream quote may not be available to you at all.
Young and newly qualified drivers
The highest premiums in the market, and the segment where insurer appetite varies most. Being a named driver on a family policy is usually cheaper but builds no discount of your own.
Learner drivers
Not every insurer accepts learner permit holders, so the comparison set is smaller than it looks. Cover arrangements and test day documentation both need checking.
Drivers over fifty
Often among the better rated profiles, particularly with low mileage and a full discount, and some insurers price this group specifically.
Electric vehicle drivers
Repair costs, battery handling and approved repairer networks all affect pricing, and not every insurer is equally comfortable with EVs.
Households with more than one car
Insuring several vehicles under one arrangement can reduce the household total and simplify renewals.
Overseas licences or driving history
How your previous experience and no claims history are recognised varies considerably between insurers, and it materially changes the quote.
Anyone using the car for work
Delivery, courier, rideshare or carrying tools and stock. Personal policies generally exclude this, and a claim during business use on a social policy is a declined claim.
When a broker earns its keep
If you fall into any of these, comparing three online quotes may simply return three refusals. That is the point at which a broker is doing something a comparison form cannot.
Telematics and usage based policies
Some Irish insurers offer policies that price partly on how and when you actually drive, measured through a device in the car or a phone app. These are most commonly aimed at younger drivers.
How they work: the policy monitors some combination of mileage, speed, braking, acceleration and time of day, and adjusts the premium or offers a renewal discount based on the resulting score.
Worth considering if you
Are a younger driver facing high standard quotes, drive relatively little, and do not drive late at night.
Less attractive if you
Have unpredictable driving patterns, cover high mileage, or are uncomfortable with the monitoring.
Compare these against standard quotes on total expected cost, not just the opening premium, and read the terms on what happens if the score drops or the device is removed.
Never let your cover lapse between policies
A gap in continuous insurance is one of the more expensive mistakes available, and it is entirely avoidable.
Driving uninsured is a serious offence. Beyond that, a break in cover affects future pricing, because insurers ask about continuous insurance history and a gap has to be explained. It can also interrupt your no claims discount, since most insurers will only accept a discount from a policy that ended within the last two years.
When switching
- ✓Confirm the new policy and its start date in writing before cancelling the old one.
- ✓Line the start date up with the existing expiry date, with no gap.
- ✓Do not cancel first and arrange cover afterwards.
- ✓If you are selling a car and buying another, keep the policy live and transfer it rather than cancelling.
Check the quote before you buy
Before you accept anything, confirm:
- ✓The cover level is what you intended to buy
- ✓The excess is affordable, including any additional excesses
- ✓Your mileage, class of use and parking details are accurate
- ✓Every named driver is listed, with the correct details
- ✓Your no claims discount is correctly recorded
- ✓The extras you decided you needed are actually included
- ✓The start date leaves no gap in cover
- ✓The total amount payable over twelve months is what you expect
Then read the policy document, not just the schedule. It takes fifteen minutes and it is the only place the exclusions are written down in full.
Talk to a broker before you accept a renewal
Comparing car insurance quotes in Ireland is straightforward in principle and tedious in practice, which is why most people renew without checking and pay for the privilege. The work is in making the comparison genuinely like for like, and in knowing which insurers are worth approaching for your particular profile.
Money Maximising Advisors is an independent financial advisory and insurance brokerage based in Galway, regulated by the Central Bank of Ireland, reference C154250. We compare motor insurance across our panel of insurers, including the awkward cases that online forms turn away, and we can review the rest of your cover across the wider general insurance market at the same time.
Renewal coming up?
Find Out Where Your Current Price Actually Sits
Send us your details and we will compare your motor insurance across our panel of insurers.
Important information
This article is general information only and does not constitute financial or legal advice. Cover, limits, exclusions, excesses and acceptance criteria vary between insurers and are subject to individual underwriting. Market figures and regulatory requirements are summarised from Central Bank of Ireland and Competition and Consumer Protection Commission sources current at the time of writing. Confirm current requirements with your insurer or broker.